


 281
/ 7 MIN READ

The Indian fashion retail market 2025 marked a quiet but decisive turning point. Across luxury, menswear, and family-focused categories, brands moved away from overt statements and seasonal hype toward restraint, meaning, and long-term relevance. What united these shifts was a deeper understanding of the modern consumer—one who values emotional connection, versatility, and responsibility as much as design.
Menswear Learns to Speak Softly
In menswear, luxury softened its voice. Rather than commanding attention, it began to express confidence through precision, fabric innovation, and ease of wear. Customers showed a clear preference for silhouettes that could be worn repeatedly and adapted across occasions, reflecting how lifestyles themselves have blurred.
“This year, we saw luxury shift from loud statements to quiet confidence. Minimal design, sharper fits, and subtle detailing took centre stage, with customers increasingly asking for timeless, repeat-wear pieces rather than trend-led buys,” shared Shrey Vij, Founder of Philocaly Menswear.
Refined Simplicity Takes Centre Stage
A similar recalibration was evident at Corneliani, where refined simplicity emerged as a defining theme. Menswear in 2025 became far more intentional, shaped by soft tailoring, lighter constructions, relaxed silhouettes, and a renewed focus on craftsmanship and fabric innovation. Timeless elegance continued to resonate—but with a modern ease that mirrors how men dress today. Luxury, increasingly, was less about excess and more about authenticity, versatility, and comfort.
“2025 marked a shift toward more intentional menswear,” said Salesh Grover, Business Head, OSL Luxury Collections & Corneliani. “Refined simplicity came to the fore through soft tailoring, lighter constructions, and relaxed silhouettes, alongside a renewed focus on craftsmanship and fabric innovation. Timeless elegance still resonated, but with a modern ease that reflects how men dress today. As we look to 2026, menswear will continue to balance tradition with innovation, with sustainable materials, seasonless dressing, and versatile pieces shaping the future of luxury.”
Occasion Wear Moves Toward Understated Power
This shift was especially visible in occasion wear, traditionally driven by grandeur and one-time use. At Philocaly, understated wedding silhouettes gained momentum, with men seeking clothing that felt powerful yet effortless rather than ornamental.
“We noticed a 30% increase in understated wedding silhouettes, with men choosing clothing that feels powerful yet effortless,” Vij added.
Fabric Innovation Becomes Foundational
Looking ahead, fabric innovation is expected to play a defining role in how menswear evolves. As work, travel, and celebration continue to overlap, functionality is no longer optional—it is foundational to modern luxury. Linen blends, hemp, bamboo, and performance materials are increasingly shaping how garments breathe, move, and endure.
Redefining Luxury Beyond Ownership
Beyond apparel, the idea of luxury itself is being redefined. As access expands, aspiration is no longer tied to accumulation but to introspection and emotional resonance. This philosophical shift is shaping how premium brands articulate value.
“Luxury today is undergoing a fundamental shift,” said Manikaran Khurana and Rose Kundu, Founders of Cravings. “As affluence expands globally, meaning shrinks. The modern consumer is no longer impressed by what can be owned, but moved by what speaks to their inner voice and has soul.” For such consumers, luxury is less about abundance and more about depth—an idea that resonates strongly in a post-excess world.
Values Shape the Future of Family Fashion
This growing emphasis on values and intention is also reshaping family and children’s fashion, where trust and transparency are becoming critical purchase drivers. Parents today are not only style-conscious but deeply aware of sourcing, materials, and long-term impact. The team at Ed-a-Mamma observed that sustainability has moved from being a brand differentiator to a baseline expectation within the kids’ and maternity clothing category. “Parents are increasingly asking where products come from, how they are made, and the values they represent,” the team shared, noting that this shift has supported strong business momentum alongside retail expansion.
Looking Ahead: From Intention to Execution
As the industry looks toward 2026, the focus is shifting from intention to execution—embedding conscious thinking into every layer of the value chain, from materials to ecosystem building. Whether through smarter tailoring, quieter luxury narratives, or responsible family brands, Indian fashion is no longer chasing visibility for its own sake. Instead, it is learning to listen—to lifestyle shifts, emotional needs, and ethical expectations. The future of fashion, it seems, is less about making noise and more about making sense.


India’s at-home services market is evolving as consumers increasingly seek professional beauty treatments, grooming, appliance repairs, and household support without leaving their homes. Digital platforms are bringing these services online, creating opportunities for organized players in a largely unorganized industry.
Changing lifestyles and rising expectations around convenience are driving adoption. However, sustained growth will depend on more than making services accessible. Platforms must ensure consistent quality, transparent pricing, and reliable service delivery to encourage repeat bookings.
For beauty and grooming platforms, the shift is creating demand for a wider range of services at home. Yes Madam, for instance, is seeing growing interest in specialized treatments, including Hydra Derma Facials, Laser Hair Reduction, and spa services. The company’s operating revenue increased from Rs 94 crore in FY25 to Rs 195 crore in FY26.
“Customers are no longer booking at-home services only for everyday grooming. They are also exploring premium skincare, spa services and advanced treatments that were traditionally only available at salons or skin clinics,” shared Aditya Arya, Co-founder and CEO, Yes Madam.
Similarly, Billu Salon also observes convenience and affordability driving demand for home-based grooming.
"Consumers are increasingly looking to save time while maintaining expectations around service quality," expressed Nilesh Kothari, Founder, Billu Salon.
While beauty and grooming platforms are expanding their reach, appliance service providers are addressing a different set of consumer concerns, including repair costs, technician reliability, and after-sales support. Saurabh Luthra, Co-founder and CEO of Eazzy, said changing expectations around service availability are creating opportunities across the broader home-services market.
“Quick commerce taught urban India to expect a stranger at the door within the hour, and that expectation transferred to household work,” Luthra added.
Beauty and Grooming Move Beyond Traditional Salon Visits
For consumers, at-home beauty services offer flexibility while eliminating travel and waiting times. The model is particularly relevant for working professionals and households seeking convenient access to grooming and wellness services.
Kothari said time savings and affordability are central to the growing preference for home-based grooming.
“The clients are looking for good quality of service at a reasonable price. They are willing to pay some additional amount of money for the sake of convenience, but they have high expectations of the service.”
At Yes Madam, consumer interest is also extending beyond routine grooming to specialized treatments and premium experiences. The company is broadening its portfolio to cater to customers who want salon-style services without visiting a physical location.
The two businesses, however, follow different approaches to service delivery. Yes Madam has a network of more than 10,000 service professionals, according to Arya. Its onboarding process includes profile screening, skill assessments, and training in hygiene, product usage, and customer experience.
“For us, building a strong service partner network has always been as important as growing the customer base. After all, when a customer books a service at home, it is the professional who ultimately delivers that experience,” Arya said.
Billu Salon follows a directly managed model, with professionals employed on its payroll and undergoing regular training and performance assessments. Kothari said this helps the company identify areas where individual stylists need improvement.
“Quality is our top concern. We have our own employees who are on our payroll, and we train them regularly."
For both businesses, maintaining service quality is essential to building customer confidence and encouraging repeat bookings. While the range of treatments and operating models may differ, the ability to deliver a dependable experience at home remains central to their growth.
Appliance Repairs Bring New Opportunities to the At-Home Services Market
Beyond beauty and grooming, digital platforms are extending the at-home services model to appliance repairs and maintenance. Here, customer expectations center on transparent pricing, reliable diagnosis, genuine spare parts, and support if a repair does not resolve the problem. One of the biggest barriers to booking repairs is uncertainty around costs. Luthra believes upfront pricing can help reduce friction and make the process more transparent.
“The biggest friction in repair is not knowing the cost until the machine is already open. An upfront quote removes a negotiation most people dread.”
Eazzy also provides a 30-day post-completion support window, according to Luthra, alongside its focus on warranties and service accountability.
Unlike beauty services, which often depend on repeat appointments and expanding treatment portfolios, appliance care can also create opportunities around product replacement and resale. Eazzy is developing this additional revenue stream through recommerce, which involves buying back unwanted devices, refurbishing them, and reselling them.
Luthra said recommerce revenue overtook service revenue in July and accounted for close to 80% of the company's revenue in August.
“The interesting shift is that recommerce overtook service revenue from July onward, and accounted for close to 80% of revenue in August. That wasn't a pivot. It's the natural consequence of being inside the home at the exact moment a customer decides a device isn't worth fixing.”
This model allows the company to build additional business around the point at which customers decide whether to repair, replace, or sell an appliance.
Technology and Service Networks Support Growth
Across beauty, grooming, and appliance care, technology is increasingly being used to manage more than discovery and bookings. Demand forecasting, professional allocation, customer support, and post-service assistance are becoming important parts of the operating model.
Arya said Yes Madam has evolved from manually recording appointments in its early days to offering app-based service discovery, pricing, and bookings. The company also uses demand forecasting to plan product supplies and identify locations that require additional professionals. It is developing an AI-powered chatbot to handle customer queries.
Billu Salon also sees technology as a way to simplify bookings and payments, although Kothari believes digital access must be supported by reliable execution.
“Good service still depends on trained people and proper execution.”
At Eazzy, technology supports upfront pricing, appointment scheduling, technician tracking, and customer assistance through its app and WhatsApp. Luthra said operational efficiency depends on coordinating the right professional, parts, and service location for each job.
“Fulfilment is where most of the hard engineering sits: routing the right skill to the right job, parts availability, and knowing when a job needs a workshop instead of a home visit.”
The operating requirements vary by category, but all three businesses need systems that can match customer demand with the right professionals while maintaining consistent service standards.
Expansion Beyond Major Cities
As awareness of organized at-home services grows, companies are exploring opportunities beyond major metropolitan areas. However, expansion requires more than making an app available in a new market. Businesses must establish local professional networks, build sufficient demand, and maintain service quality across locations.
Yes Madam already serves customers in Tier II and Tier III cities, according to Arya, where consumers are gradually shifting from traditional salons to at-home beauty services. The company is also strengthening its presence in markets including Delhi-NCR, Bengaluru, Mumbai, Hyderabad, Pune, Kolkata, and Ahmedabad.
Billu Salon plans to expand beyond Delhi-NCR into markets including Mumbai, Bengaluru, Chennai, Hyderabad, Pune, Ahmedabad, Surat, and Raipur. Kothari said the company intends to strengthen its existing business and move closer to break-even before expanding further.
Eazzy sees opportunities in smaller towns where authorized appliance service networks can be limited. Luthra said partner-led coverage could help address these gaps while expanding access to organized repair services.
The Road Ahead
India’s at-home services market offers significant growth potential, but its next phase will depend on repeat bookings, efficient operations, and customer trust.
Yes Madam is expanding its beauty and wellness portfolio, while Billu Salon is prioritizing service quality and geographic expansion. Eazzy, meanwhile, is connecting appliance maintenance with recommerce opportunities, demonstrating how platforms can build additional revenue streams beyond individual service transactions.
For Luthra, the broader opportunity lies in organizing a fragmented industry.
“Online home services will roughly double by FY30, but will still be a low single-digit share of a ₹5 lakh crore market. So the real contest isn't platform versus platform. It's organised versus unorganised.”
As consumers increasingly turn to digital platforms for services at home, businesses will need to combine convenience with transparent pricing, skilled professionals, and dependable execution. Online discovery may bring customers to a platform, but consistent service quality will determine whether they return.
India’s beauty and personal care market is expanding as consumers spend more on skincare, cosmetics, haircare, and grooming products. According to IMARC Group, the Indian beauty and personal care market was valued at $31.19 billion in 2025 and is projected to reach $48.72 billion by 2034. Rising beauty awareness, digital discovery, and demand for specialised products are creating opportunities for brands to expand their distribution networks.
For direct-to-consumer (D2C) beauty brands, physical retail is emerging as an important growth channel. While e-commerce enables convenient shopping and product discovery, offline stores allow consumers to test makeup shades, assess product textures and seek recommendations. CBRE reported that D2C brands accounted for 18 percent of India's retail leasing activity in the first half of 2025, compared with 8 percent in the same period of 2024. The shift highlights how digital-first businesses are increasingly combining online sales with physical retail to reach more consumers.
Why D2C Beauty Brands Are Expanding Offline
Beauty purchases often involve personal preferences and product evaluation. Physical stores help consumers make informed choices while giving brands opportunities to improve visibility, attract new customers, and encourage repeat purchases. However, expansion also brings challenges such as rental expenses, inventory management, and store-level profitability.
Against this backdrop, five D2C beauty brands are building their presence beyond online platforms.
Top 5 D2C Beauty Brands Expanding Their Offline Presence
1. SUGAR Cosmetics
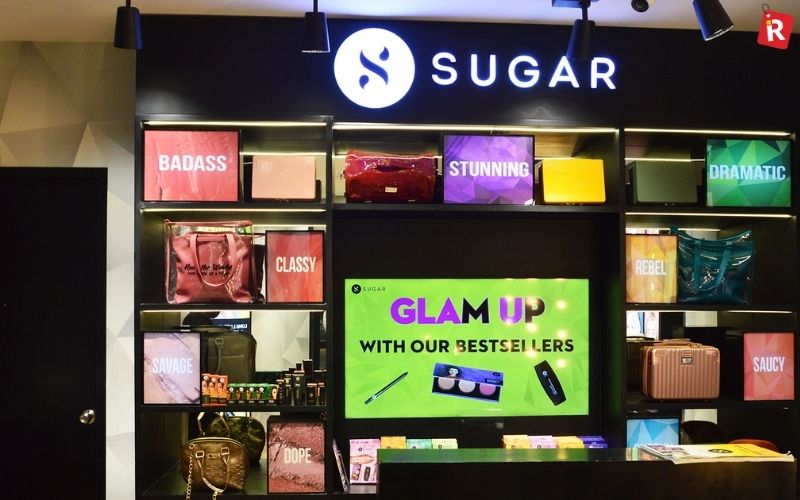
SUGAR Cosmetics has built its identity around makeup products for Indian consumers, including lipsticks, foundations, and eye makeup. After establishing a strong digital presence, the brand expanded through exclusive outlets and retail partnerships. In 2025, the company reported a presence across more than 550 cities and over 50,000 retail touchpoints. Its offline network allows consumers to test shades, compare finishes, and explore products before purchasing.
Physical retail is particularly relevant for colour cosmetics, where shade matching and texture influence buying decisions. For SUGAR, the priority is to make its stores commercially sustainable while maintaining consistent product availability and customer experience across online and offline channels.
2. Plum
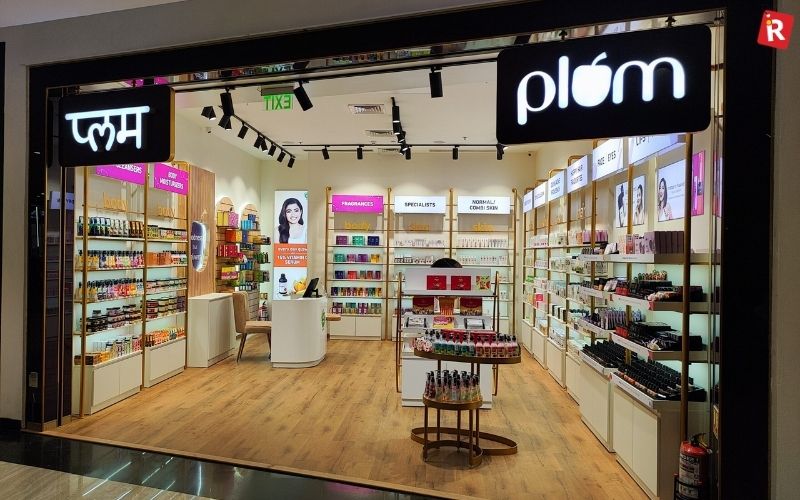
Founded in 2013, Plum focuses on vegan beauty and personal care products across skincare, haircare, body care, and cosmetics. Its digital-first model helped the brand communicate product ingredients and routines, while its offline presence has widened access to its portfolio. Plum products are available through exclusive stores and selected retail outlets, alongside its online channels. Physical retail enables customers to explore cleansers, moisturisers, sunscreens and other products before choosing what suits their needs.
The brand's opportunity lies in combining product education with accessibility. Maintaining consistent information, availability, and service across channels will remain important as it expands its retail footprint.
3. Minimalist
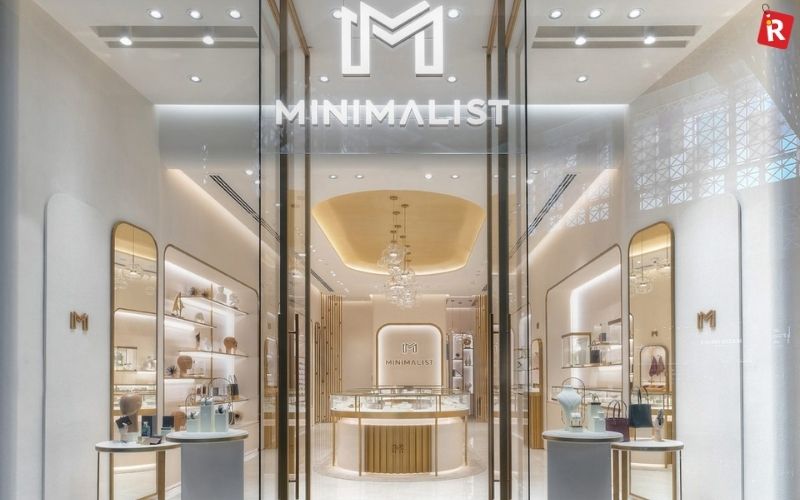
Minimalist built its reputation around ingredient-focused skincare and formulations targeting specific consumer concerns. Its digital-first approach appealed to shoppers seeking greater transparency about skincare ingredients. In 2025, Hindustan Unilever agreed to acquire a 90.5 percent stake in Minimalist for Rs 3,000 crore. The partnership created an opportunity to use HUL's distribution network to expand the brand's reach.
A March 2025 report outlined plans to increase Minimalist's retail presence from approximately 2,000 stores to 20,000 over two years. This was an expansion target, not confirmation that the full network had been established. Wider distribution can improve access to serums, cleansers and moisturisers, particularly among consumers who prefer buying skincare products in physical stores. The challenge will be to retain the brand's ingredient-led positioning while ensuring accurate product information and appropriate consumer guidance.
4. Pilgrim
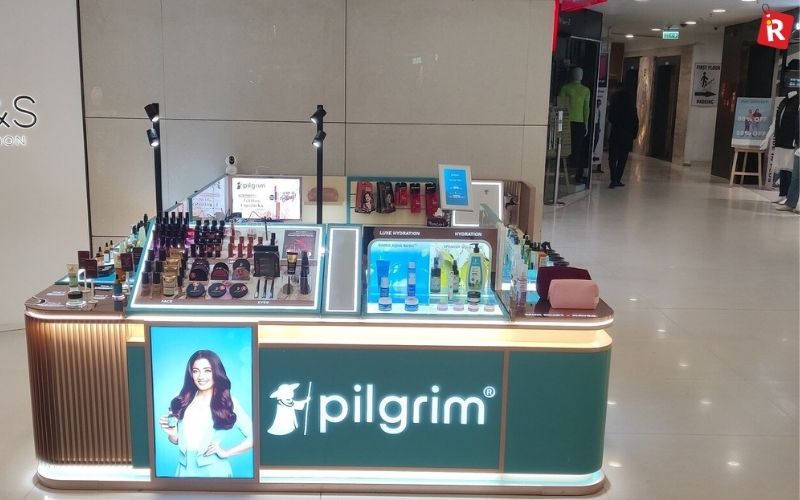
Pilgrim has developed a multi-category beauty and personal care business covering skincare, haircare, makeup and fragrances. Its digital presence has supported product discovery, while offline distribution has created additional opportunities to reach consumers. In March 2025, The Economic Times reported that Pilgrim products were available in more than 10,000 retail stores across India. At the time, the company stated that offline sales contributed approximately 20 percent of its revenue and outlined plans for further expansion.
Its diverse portfolio offers several opportunities for in-store discovery. Customers can explore skincare products, evaluate fragrances, and discover makeup through retail outlets rather than relying solely on online descriptions. Pilgrim's next phase of growth will depend on balancing exclusive outlets with broader retail distribution while maintaining product availability and controlling expansion costs.
5. Mamaearth
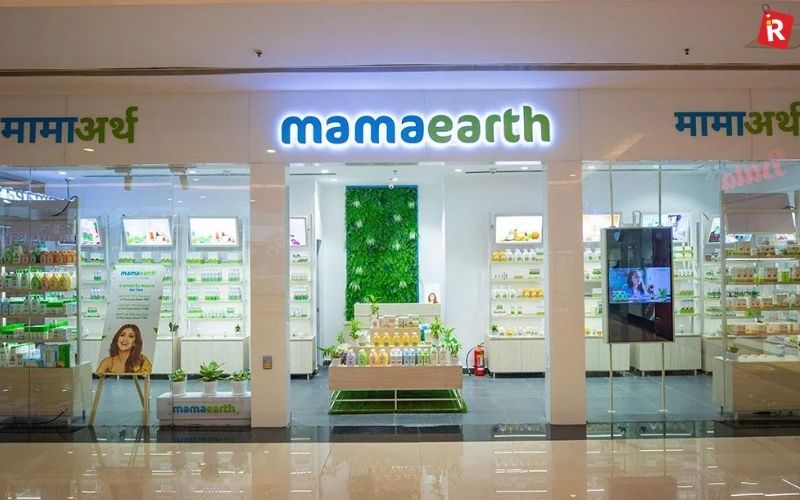
Mamaearth entered the market as a digital-first personal care brand, with products across skincare, haircare, baby care, and everyday grooming. Its move into physical retail reflects the growing importance of offline distribution for online-originated businesses. For a brand offering frequently purchased personal care products, retail availability can support repeat purchases and improve access for consumers who prefer shopping in neighbourhood stores or organised retail outlets.
Physical shelves also offer opportunities to introduce customers to related categories, including face washes, moisturisers and shampoos. However, wider distribution must translate into sustainable sales rather than simply increasing the number of outlets. Inventory management, product placement and consistent availability will remain central to Mamaearth's ability to strengthen its omnichannel business.
The Road Ahead for D2C Beauty Retail in India
The expansion of D2C beauty brands into physical retail reflects a broader shift in India's consumer market. Online platforms remain important for discovery and convenience, while stores offer product trials, immediate purchases, and greater accessibility. For brands, the challenge is to ensure that offline expansion improves customer acquisition and repeat sales without compromising profitability. Businesses that effectively integrate e-commerce, exclusive outlets and retail partnerships will be better positioned to serve India's evolving beauty consumers.
Frequently Asked Questions
1. What is a D2C beauty brand?
A D2C beauty brand sells products directly to consumers through its website, app, or exclusive stores. Many brands also use marketplaces and retail partners to expand their reach.
2. Why are D2C beauty brands opening physical stores?
Physical stores allow consumers to test products, compare shades and textures, receive guidance, and purchase products immediately.
3. Which D2C beauty brands are expanding offline in India?
SUGAR Cosmetics, Plum, Minimalist, Pilgrim, and Mamaearth are examples of digital-first beauty businesses with physical retail or broader offline distribution strategies.
4. Does offline retail replace online sales?
No. Many brands follow an omnichannel model in which websites, marketplaces, exclusive stores, and retail partners complement one another.
5. What challenges do D2C beauty brands face offline?
Key challenges include rental costs, inventory management, distribution expenses, product availability, and maintaining profitability across retail channels.
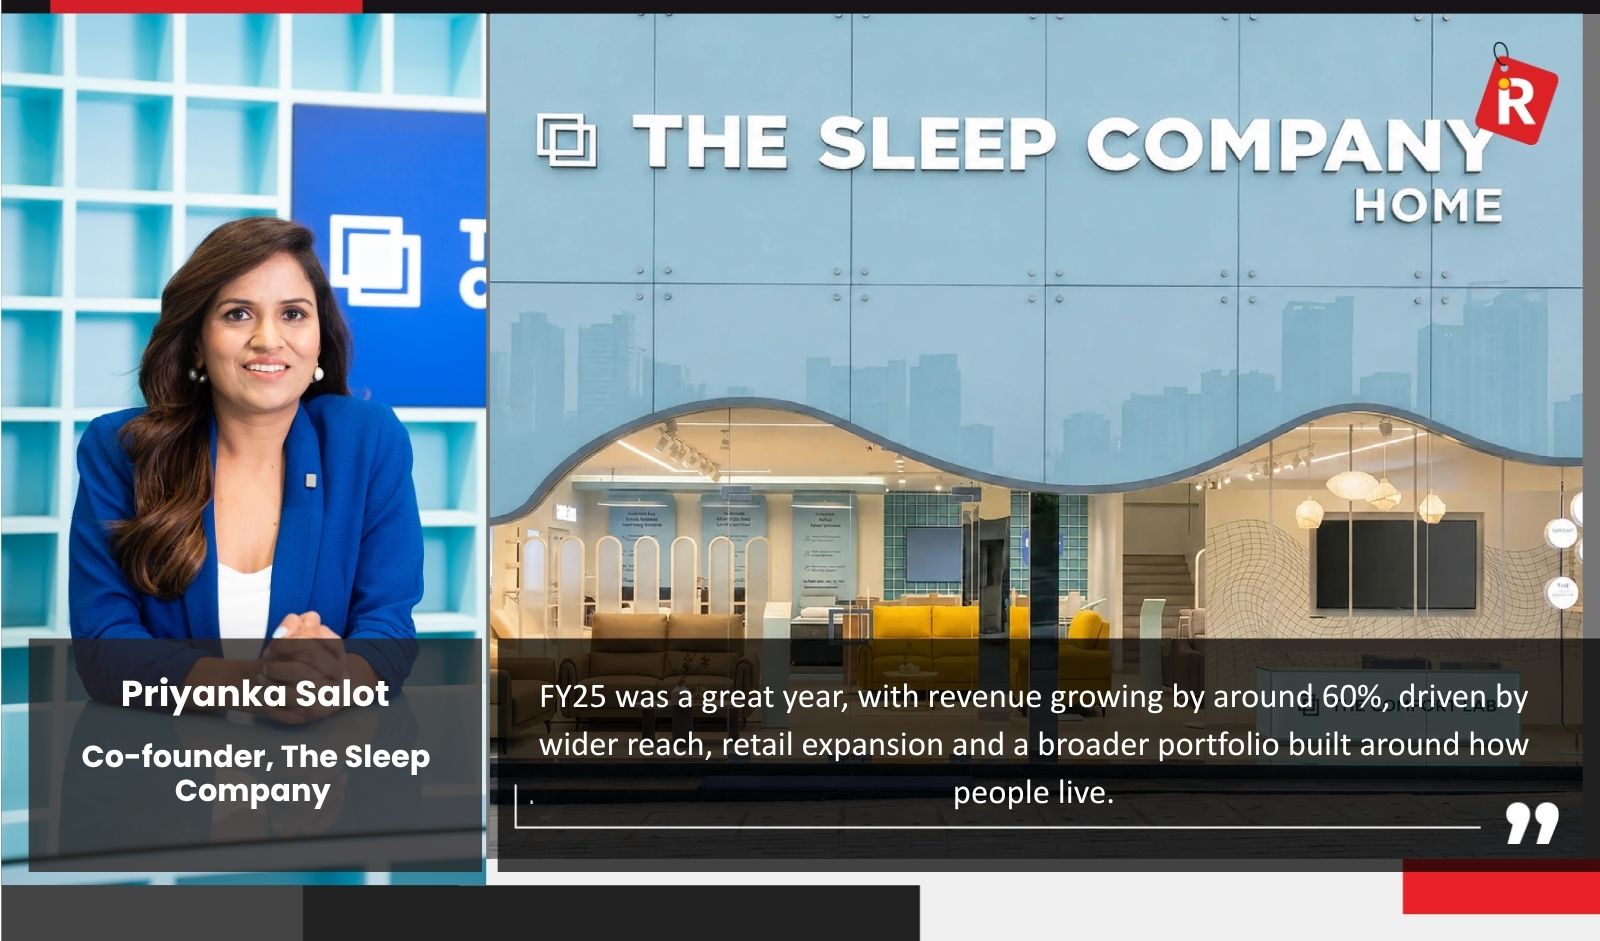
The Sleep Company is sharpening its focus on physical retail as it works towards crossing Rs. 1,000 crore in revenue, with store expansion, category diversification and deeper penetration into smaller cities shaping its next phase of growth.
The company, which reported revenue of approximately Rs. 770 crore and year-on-year growth of around 58% in FY25, currently operates more than 220 stores across over 55 cities. It plans to expand its retail network to 400 stores over the next two to three years, strengthening its reach across established markets and emerging consumption centres.
For The Sleep Company, the expansion reflects a business strategy built around experiential retail. While digital channels help consumers discover products and research their features, physical stores allow them to test mattresses, experience product technology and make more informed purchasing decisions.
“FY25 was a great year, with revenue growing by around 60%, driven by wider reach, retail expansion and a broader portfolio built around how people live. Consumers discover us online but increasingly want to experience comfort in-store before buying,” said Priyanka Salot, Co-founder, The Sleep Company.
Physical Stores Form the Core of Its Business Model
Retail has become a central component of The Sleep Company's growth strategy, contributing approximately 80% of its business, while online channels account for the remaining 20%.
The channel mix highlights the importance of physical stores in a category where comfort, material quality and individual preferences influence purchase decisions. Unlike products that can be evaluated largely through specifications or online reviews, mattresses often require consumers to experience the product before committing to a purchase.
“For us, retail is about experience, not just store count,” said Salot.
The company is therefore focusing on building stores that allow customers to understand its product range and technology through direct interaction. This approach also supports its premium positioning by helping consumers assess the differences between products and identify solutions suited to their needs.
As the network expands, the challenge will be to maintain a consistent in-store experience while increasing the number of locations. The planned addition of stores also provides an opportunity to reach consumers in Tier-II and Tier-III markets, where organised retail and demand for premium home products are creating new growth avenues.
“Online remains important for discovery, but in our category, experience is sacrosanct. Consumers want to see, touch and experience the technology before they buy,” Salot said.
Expansion Strategy Supports Rs. 1,000 Crore Revenue Ambition
The Sleep Company expects to cross Rs. 1,000 crore in revenue within the current financial year, with retail expansion, a wider product portfolio and deeper geographic penetration expected to support the target.
Its current revenue base of approximately Rs. 770 crore provides a foundation for the next phase of expansion. However, achieving the milestone will depend on the company's ability to convert its growing retail presence into higher sales while sustaining demand across its product categories.
“Retail has been our biggest growth engine, and our expanding portfolio and deeper geographic penetration will drive the next phase,” said Salot.
The company has indicated that its FY26 performance has been strong so far, although it expects full-year growth to remain broadly aligned with overall market conditions. It has not specified a separate growth rate for the financial year.
Expanding into new markets can help the company access additional consumer segments, while a broader product portfolio creates opportunities to increase sales across existing stores. Together, these initiatives form the basis of its strategy to scale beyond its current network.
From Sleep Products to Whole-Home Comfort
Alongside its store expansion, The Sleep Company is broadening its business beyond mattresses through Home Stores, an initiative focused on premium comfort-tech products for the entire home.
The move represents a shift from a sleep-focused product offering towards a wider home-comfort proposition. It could also allow the company to serve customers across more categories and strengthen the role of its stores as destinations for home-related purchases.
“We are also expanding into Home Stores, focused on premium comfort-tech products for the entire home. We see this as the next big opportunity to revolutionise how India experiences comfort,” said Salot.
For the company, category diversification offers an additional route to growth beyond opening new stores. A wider range of products could increase the relevance of its retail network, create cross-selling opportunities and support its ambition to establish itself as a broader comfort-tech brand.
The strategy also places greater importance on store design, product demonstrations and the ability to communicate the functional benefits of technology-led products to consumers.
India's Mattress and Home Furniture Markets Offer Headroom
The Sleep Company's expansion comes amid growth in India's mattress and home furniture markets.
According to Mordor Intelligence, India's mattress market was valued at approximately US$2.4 billion in 2025 and is projected to reach US$3.89 billion by 2031, growing at a compound annual growth rate (CAGR) of 8.6%.
The broader home furniture market was valued at US$25.2 billion in 2025 and is projected to reach US$40.53 billion by 2031, registering a CAGR of 8.24%, according to the same research firm.
These market projections point to opportunities for brands that combine differentiated products with wider distribution and stronger consumer engagement. For The Sleep Company, physical retail provides a platform to demonstrate product features, while its expanding portfolio allows it to address a wider range of home-comfort needs.
Scaling Retail While Broadening the Business
The Sleep Company's next phase will depend on how effectively it combines store expansion with product diversification. Its target of 400 stores, approximately 80% retail contribution and ambition to cross Rs. 1,000 crore in revenue underline the importance of physical distribution in its business model.
At the same time, the move into whole-home comfort products signals an effort to build additional growth drivers beyond mattresses. As the company expands into new markets and categories, maintaining store productivity, customer experience and operational efficiency will be important to sustaining growth.
The larger business ambition is to use its retail network not only to sell products but also to build a broader consumer-facing comfort-tech brand across India's evolving home market.
India’s wellness industry is witnessing a shift from occasional self-care and relaxation towards preventive health, personalised wellbeing and everyday wellness routines. From luxury hospitality and longevity-focused retreats to Ayurvedic products and omnichannel retail, businesses are increasingly exploring ways to integrate wellness into consumers’ daily lives.
The shift is being driven by growing awareness of holistic health, demand for natural and transparent products, and a greater emphasis on long-term wellbeing. Consumers are increasingly looking for solutions that support sleep, stress management, skin and hair health, vitality and healthy ageing, creating opportunities for businesses across hospitality, healthcare, personal care and traditional wellness systems.
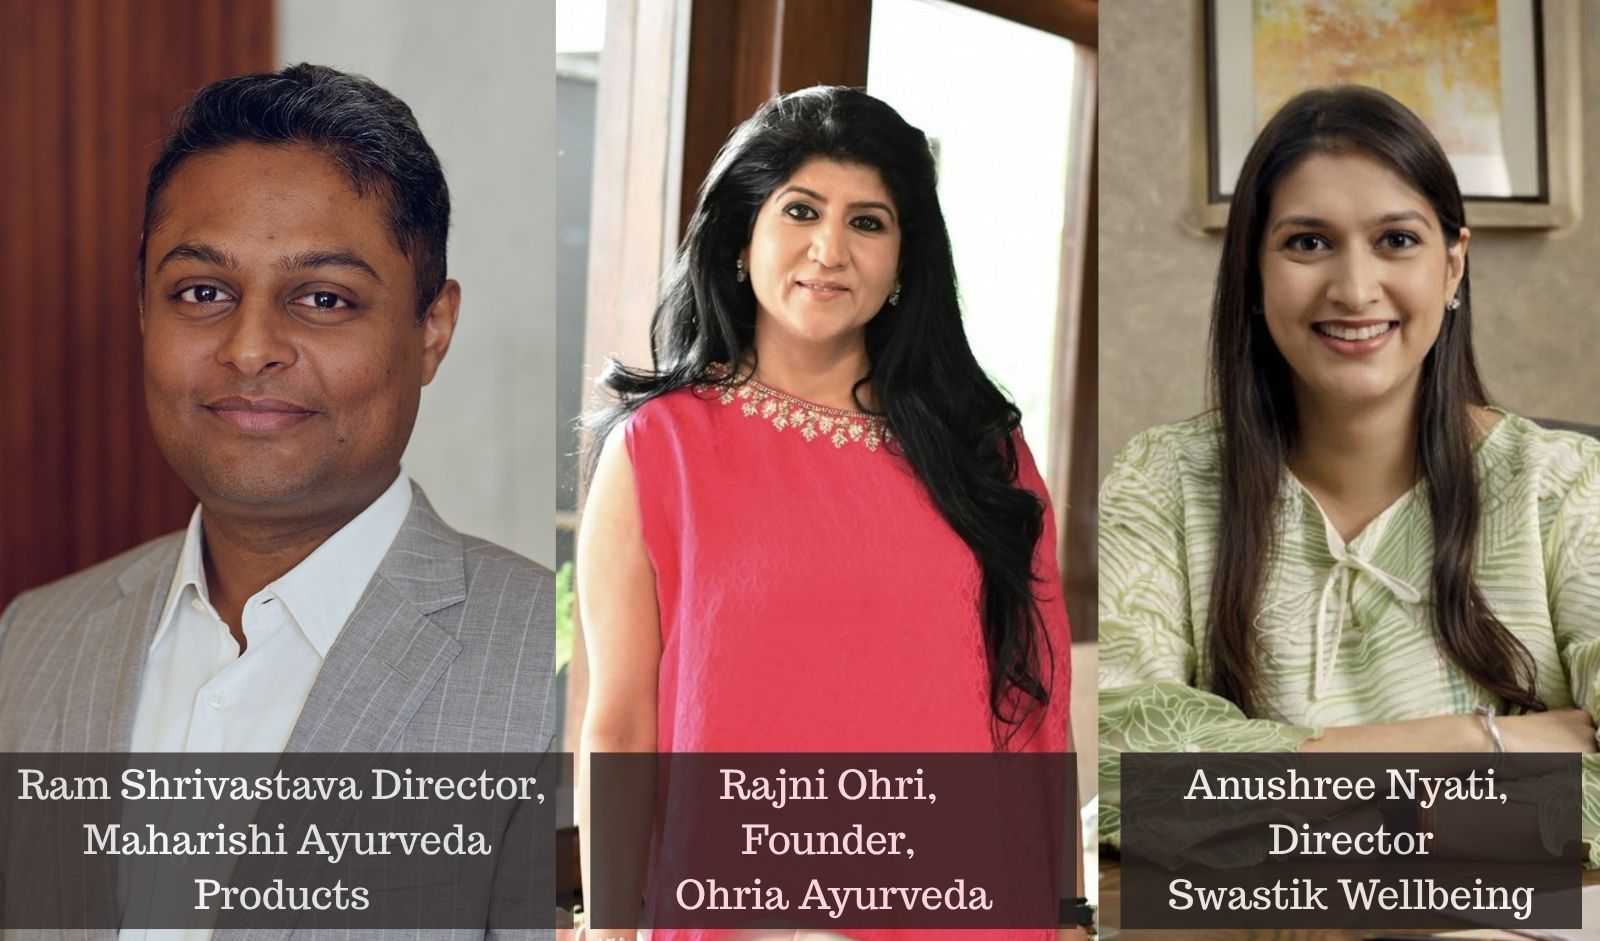
Industry players, including Swastik Wellbeing Sanctuary, Ohria Ayurveda and Maharishi Ayurveda Products, are approaching this opportunity from different segments of the wellness ecosystem, reflecting how traditional Indian wellness practices are being adapted to contemporary consumer needs.
Luxury Hospitality Shifts Towards Personalised Wellness
Luxury hospitality is increasingly exploring wellness as a core part of the guest experience, moving beyond conventional spa treatments and short-term relaxation towards personalised programmes focused on longer-term wellbeing.
According to Anushree Nyati, Director, Swastik Wellbeing Sanctuary, India has a natural advantage in this emerging segment because of its heritage of Ayurveda, yoga, meditation and spiritual healing.
“India has always had a deep relationship with healing, Ayurveda, yoga and spirituality, but wellness is now evolving from a traditional offering into personalised wellbeing supported by new technologies,” Nyati said.
She believes the next phase of luxury wellness hospitality will combine traditional healing practices with modern science, diagnostics, technology and individualised care. Rather than positioning retreats solely as destinations for relaxation, the opportunity lies in creating experiences that help guests understand their wellbeing needs and build healthier habits beyond their stay.
Nyati describes this approach as Regenerative Wellness, which brings together traditional wisdom, modern science, technology and personalised healing.
The shift also reflects changing expectations among affluent consumers, who are increasingly seeking tangible value from premium wellness experiences. Better sleep, improved energy, metabolic health, cognitive wellbeing and healthy ageing are becoming important considerations when evaluating wellness programmes.
“The future of premium wellness will depend on outcomes and personalisation rather than luxury alone. When the proposition is credible, personalised and demonstrates meaningful value, consumers are willing to make a much more significant investment in their long-term wellbeing,” she said.
However, delivering personalised experiences while maintaining commercial viability remains a challenge for wellness operators. Nyati believes businesses need structured methodologies, specialised expertise, technology and clear operating frameworks to balance therapeutic depth with operational efficiency.
For Swastik, the Swastik Method is central to this approach, bringing together different disciplines within a structured wellness framework. The company is also exploring opportunities beyond the traditional destination-resort format, including urban wellbeing centres, shorter-format experiences, partnerships and asset-light models.
Over the next three to five years, the sanctuary sees potential across India, the Middle East, Europe and selected international wellness destinations. Its stated ambition is to establish the methodology in India before expanding internationally.
Everyday Wellness Becomes a Consumer Priority
While luxury hospitality is developing immersive wellness experiences, the consumer wellness and self-care segment is witnessing a parallel shift towards products and practices that fit into everyday routines.
According to Rajni Ohri, Founder, Ohria Ayurveda, consumers are increasingly prioritising transparency, ingredient awareness and efficacy when choosing wellness products. Rather than seeking quick fixes, they are showing greater interest in solutions that align with their long-term health and lifestyle goals.
“Consumers are no longer chasing instant fixes; they’re investing in long-term wellbeing. Today’s wellness buyer is highly informed, ingredient-aware, and actively seeks clean, transparent, and efficacy-led solutions rooted in purpose and authenticity,” Ohri said.
This shift is broadening the role of wellness in everyday life. Skincare, nutrition, sleep, movement and stress management are increasingly being viewed as interconnected elements of overall wellbeing rather than isolated categories.
Ohri identifies preventive wellness, clean beauty, skin and hair health, and sleep and stress management among the categories attracting consumer interest. She also sees younger consumers playing an important role in reshaping the market by demanding transparency, credible formulations and products that combine traditional practices with contemporary lifestyles.
Demand is also extending beyond metropolitan markets. Consumers in Tier II and Tier III cities are becoming more aware of wellness options, including those rooted in traditional Indian systems such as Ayurveda.
For brands, this creates opportunities to build offerings that combine authenticity with accessibility. Partnerships with luxury hotels, healthcare providers and lifestyle businesses can further extend wellness experiences beyond conventional retail channels.
Ohri also points to sustainability as an increasingly important consideration, with consumers paying greater attention to responsible sourcing, mindful formulations, reduced waste and long-term product value.
Ayurveda Builds on Preventive Health and Everyday Consumption
The growing focus on preventive health is also influencing demand for Ayurvedic products, as consumers explore ways to incorporate traditional wellness practices into their daily routines.
According to Ram Shrivastava, Director, Maharishi Ayurveda Products, the post-pandemic period has strengthened consumer awareness of holistic health and the importance of addressing underlying health concerns rather than relying exclusively on short-term solutions.
“The biggest shift we've witnessed in consumer behaviour is the growing awareness around preventive and holistic health. Today, people are far more informed about their well-being and are paying attention to health concerns that were often overlooked in the past,” Shrivastava said.
He identifies two areas of opportunity within the category: everyday Ayurveda and foundational health. The former includes products that consumers can incorporate into existing routines, while the latter encompasses solutions aimed at supporting stress management, vitality, healthy ageing and overall wellbeing.
Everyday Ayurveda, in particular, reflects an opportunity to make traditional wellness practices more accessible without requiring consumers to make substantial lifestyle changes. Products such as herbal infusions and traditional nourishment-focused offerings can help brands position Ayurveda as part of daily living rather than something consumers turn to only when they feel unwell.
Shrivastava believes the category's long-term opportunity lies in combining the depth of Ayurvedic knowledge with scientific research and quality validation.
“Our approach begins with the consumer, not the laboratory. We first understand people's health concerns and everyday wellness needs. Our Ayurvedic experts then turn to classical Ayurvedic texts to identify time-tested solutions and develop formulations rooted in this traditional wisdom,” he said.
He added that scientific validation plays an important role in establishing the efficacy, safety and quality of formulations, helping traditional wellness brands address contemporary consumer expectations.
Omnichannel Retail and Emerging Markets Shape Growth
As wellness becomes a more regular part of consumer spending, distribution and accessibility are emerging as important considerations for brands.
For Maharishi Ayurveda Products, an omnichannel approach brings together e-commerce, online marketplaces and physical stores to reach consumers across different stages of their purchase journey.
“Today's consumers value convenience, accessibility and trust. While e-commerce has made wellness products easily available, it has also increased the number of choices consumers face. That's why it's important for us to be present across every touchpoint, whether through our website, online marketplaces, or our neighbourhood stores,” Shrivastava said.
Physical retail also provides an opportunity for consumers to understand products, interact with experts and explore traditional wellness practices. This allows brands to build familiarity and encourage repeat engagement beyond individual product purchases.
Shrivastava said Maharishi Ayurveda Products sees opportunities across established urban markets and emerging cities. Markets such as Bengaluru, Hyderabad, Chennai, Pune, Coimbatore and Kochi remain important, while cities including Ludhiana, Nashik, Nagpur, Mysuru, Mangaluru, Visakhapatnam, Rishikesh and Puducherry are also part of the company's broader growth focus.
Strengthening distribution and consumer engagement across these markets will be important as the company seeks to expand its reach.
For the wider industry, the combination of digital discovery, physical retail, partnerships and experiential engagement offers multiple ways to connect with consumers. The challenge is to maintain consistency in product quality, customer experience and brand credibility across these channels.
Traditional Wisdom Meets Modern Wellness
Despite operating across different segments, Swastik Wellbeing Sanctuary, Ohria Ayurveda and Maharishi Ayurveda Products share a common emphasis on integrating traditional wellness knowledge into contemporary lifestyles.
For luxury hospitality, the opportunity lies in developing personalised experiences that extend beyond a short stay. For consumer wellness brands, it lies in making everyday routines more accessible, while for Ayurvedic product companies, the focus is on combining traditional formulations with modern research, retail and distribution.
The next phase of the industry will depend on how effectively businesses translate consumer interest into credible offerings, sustainable operating models and experiences that deliver lasting value.
As Nyati puts it, “We should not dilute our traditions to make them global. At the same time, we need to make them understandable, measurable and relevant to modern lifestyles.”
For India's wellness industry, this convergence of traditional knowledge, personalisation, science and accessibility could help establish wellness as a more integral part of both consumer lifestyles and the country's premium hospitality and retail landscape.
The festive season brings a packed calendar of celebrations, from Navratri gatherings to Karwa Chauth festivities. While makeup and festive outfits often take center stage, a well-rounded beauty routine begins with skincare, hydration and grooming. Preparing the skin in advance can help create a smoother base for makeup, while regular hair and body care can add to an overall fresh, well-groomed look.
For consumers looking to update their festive beauty shelves, several beauty and personal-care brands offer products across skincare, haircare, body care and grooming. From accessible beauty essentials to Ayurvedic-inspired formulations and nature-led personal care, here are five brands to explore for your Navratri and Karwa Chauth beauty routine.
5 Skincare and Grooming Brands to Add to Your Festive Routine
1. Insight Cosmetics: Everyday Beauty and Skincare Essentials
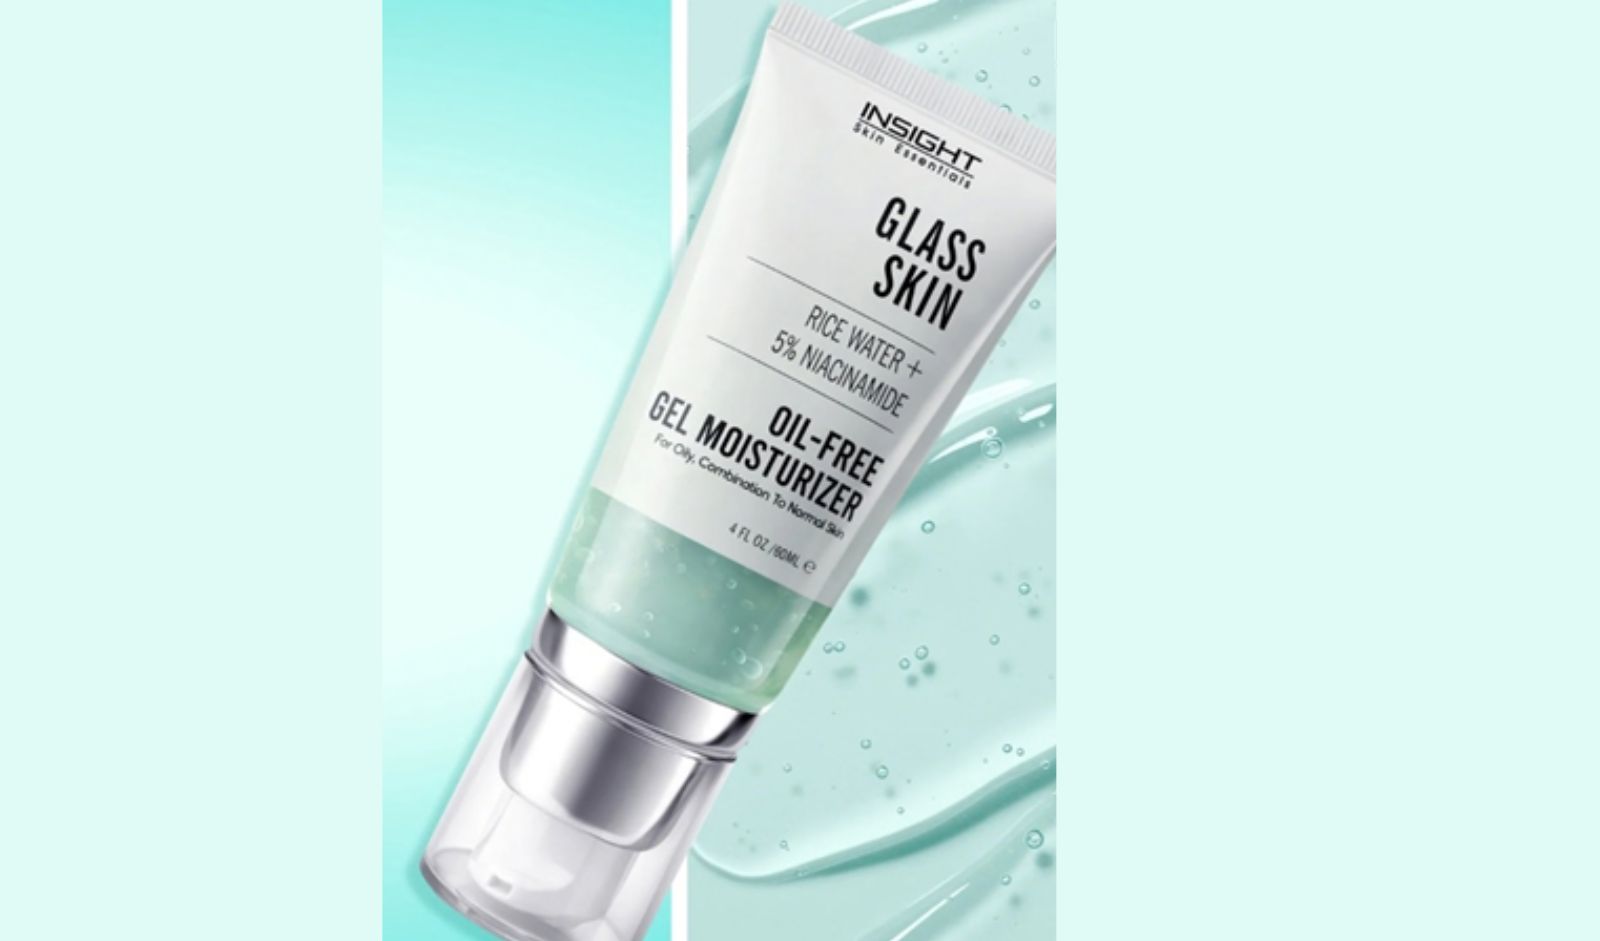
Known for making beauty accessible, Insight Cosmetics offers products beyond makeup, with a skincare portfolio designed around everyday needs. Its range includes essentials for hydration, brightening, sun protection, skin preparation and targeted care.
For festive occasions, skincare can be an important first step before applying makeup. Hydrating products can help keep the skin feeling comfortable, while suitable sunscreen supports daily sun protection. Skin-prep products can also help create a more even base for festive makeup looks.
Why explore the brand: Insight Cosmetics is worth considering for consumers looking to bring everyday skincare and makeup preparation into one beauty routine.
2. Suroskie: Skincare and Skin Prep for a Festive Glow
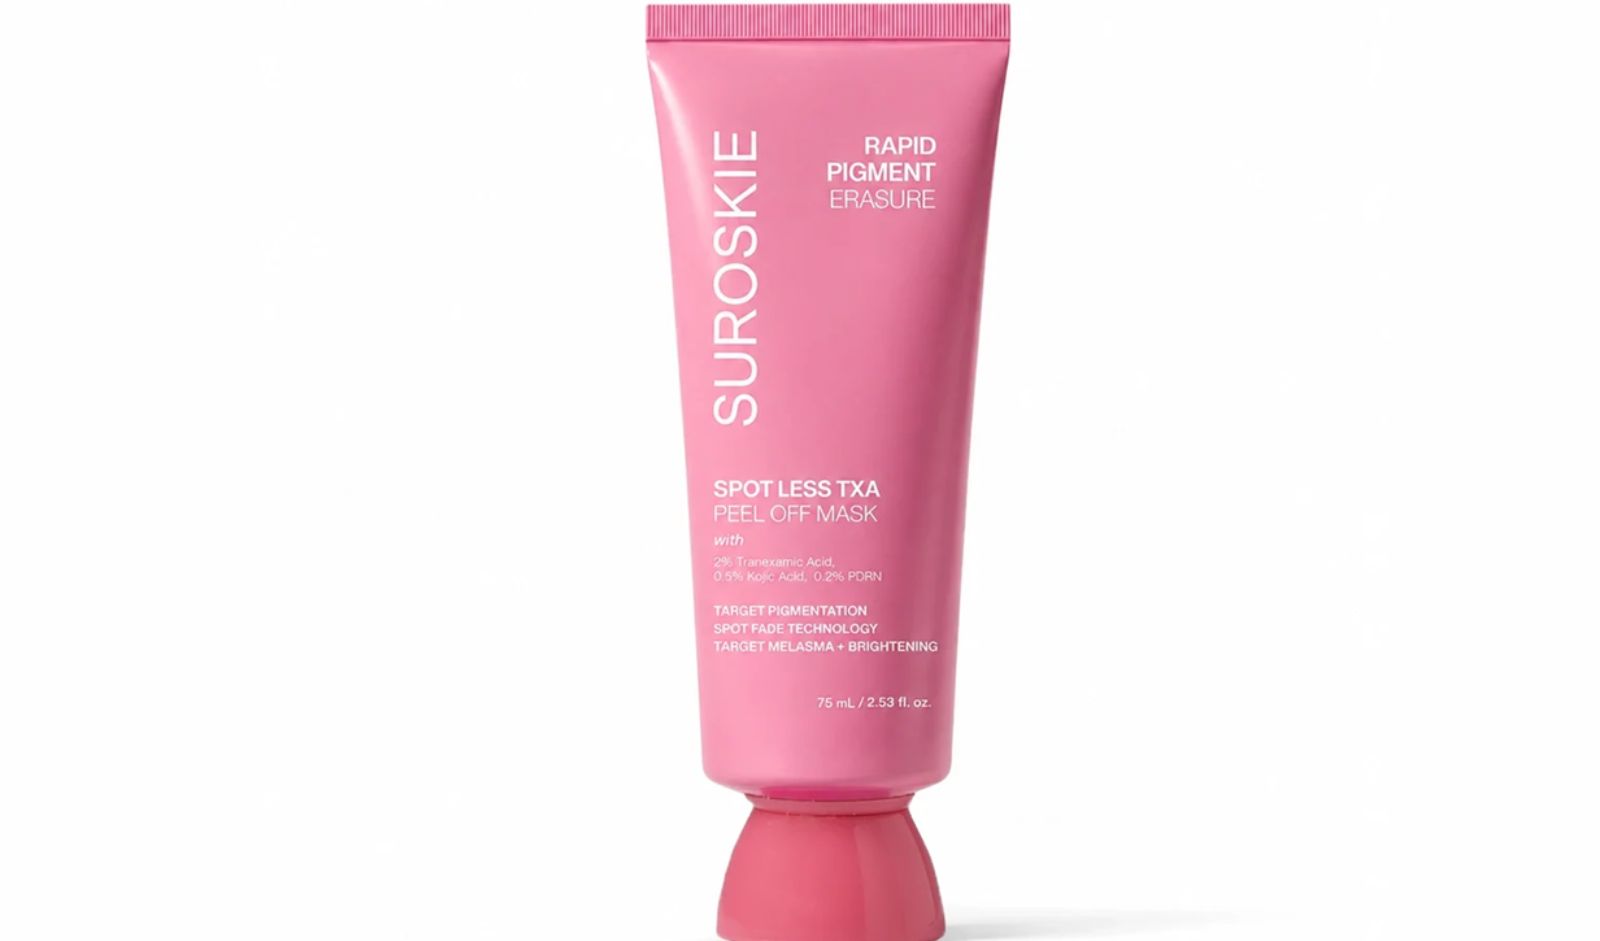
For consumers who prefer to focus on skincare before reaching for makeup, Suroskie offers a portfolio spanning cleansers, face washes, masks, scrubs, moisturizers, serums, sunscreens, face mists and makeup fixers.
A simple routine can begin with cleansing and moisturizing, followed by sunscreen during the day. Depending on individual skin needs, serums and masks can be added to support specific skincare goals. Face mists and makeup fixers may also be useful additions when getting ready for festive events.
Why explore the brand: Suroskie brings together everyday skincare and makeup-preparation products, making it an option for consumers building a routine around cleansing, hydration and a fresh-looking finish.
3. Ashpveda: Ayurvedic-Inspired Skincare, Haircare and Body Care
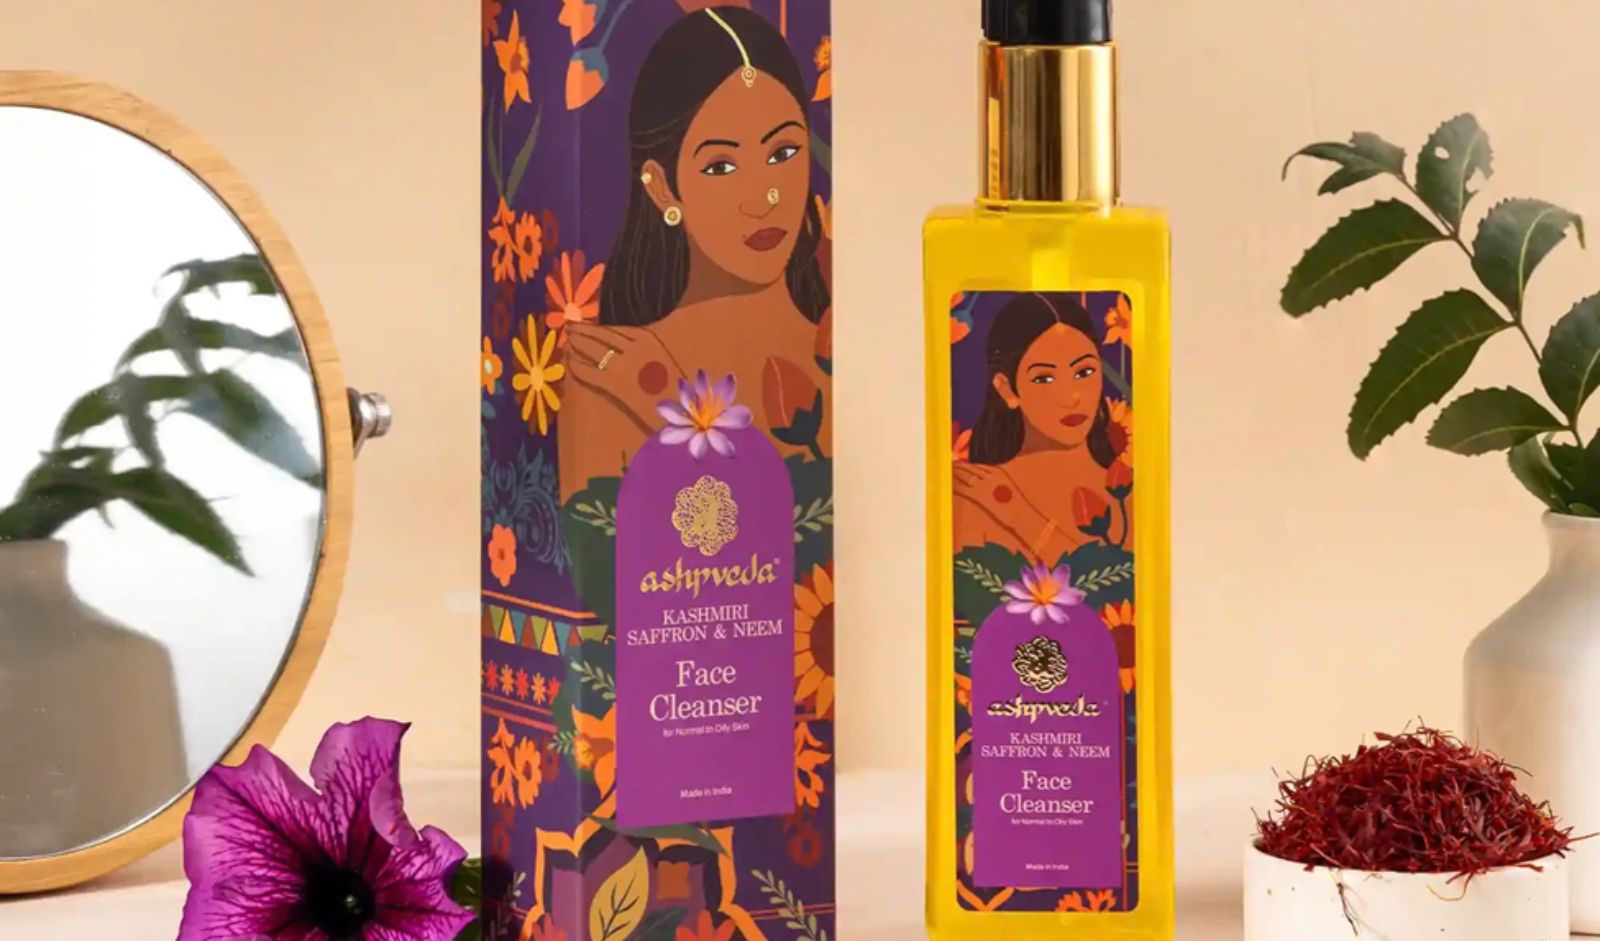
Ashpveda combines traditional Ayurvedic ingredients with modern approaches to personal care. Its portfolio spans skincare, haircare and body care, with products intended to address concerns such as dryness, dullness, pigmentation, acne, tanning and sun protection.
For festive preparation, the brand offers an option for consumers interested in incorporating Ayurvedic-inspired products into their regular routines. Rather than relying on last-minute treatments, maintaining consistent cleansing and moisturizing habits can help support the skin's comfort and appearance through a busy celebration schedule.
Why explore the brand: Ashpveda brings a traditional ingredient-led approach to contemporary personal care, with options across multiple skincare and grooming categories.
4. Wildflower Naturals: Nature-Inspired Skincare and Everyday Self-Care
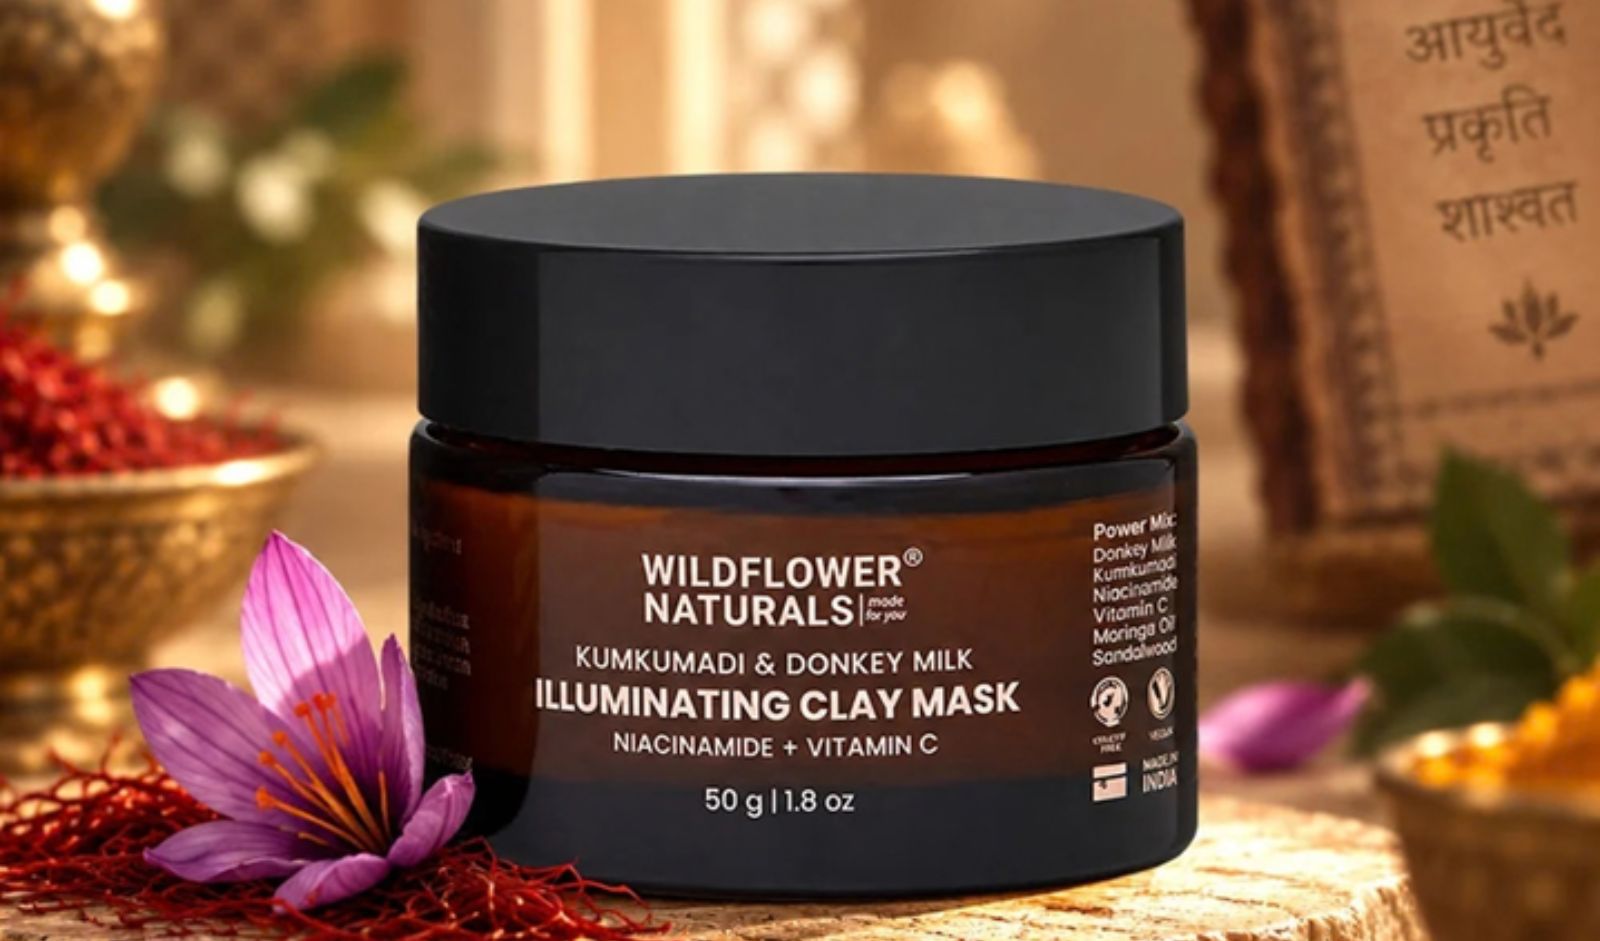
Wildflower Naturals combines nature-inspired skincare with modern actives and everyday personal-care rituals. Its portfolio covers face care, body care, men's care, fragrance and gifting, with skincare products addressing concerns such as hydration, dullness, pigmentation, uneven texture and skin radiance.
The brand's range can appeal to consumers looking to extend their festive preparation beyond facial skincare. Body care and fragrance can complement a personal grooming routine, while face-care products can be selected according to individual needs.
Why explore the brand: Wildflower Naturals offers a mix of skincare, body care, fragrance and grooming categories for consumers looking to build a broader festive self-care shelf.
5. FURR by Pee Safe: Beauty and Grooming from Head to Toe
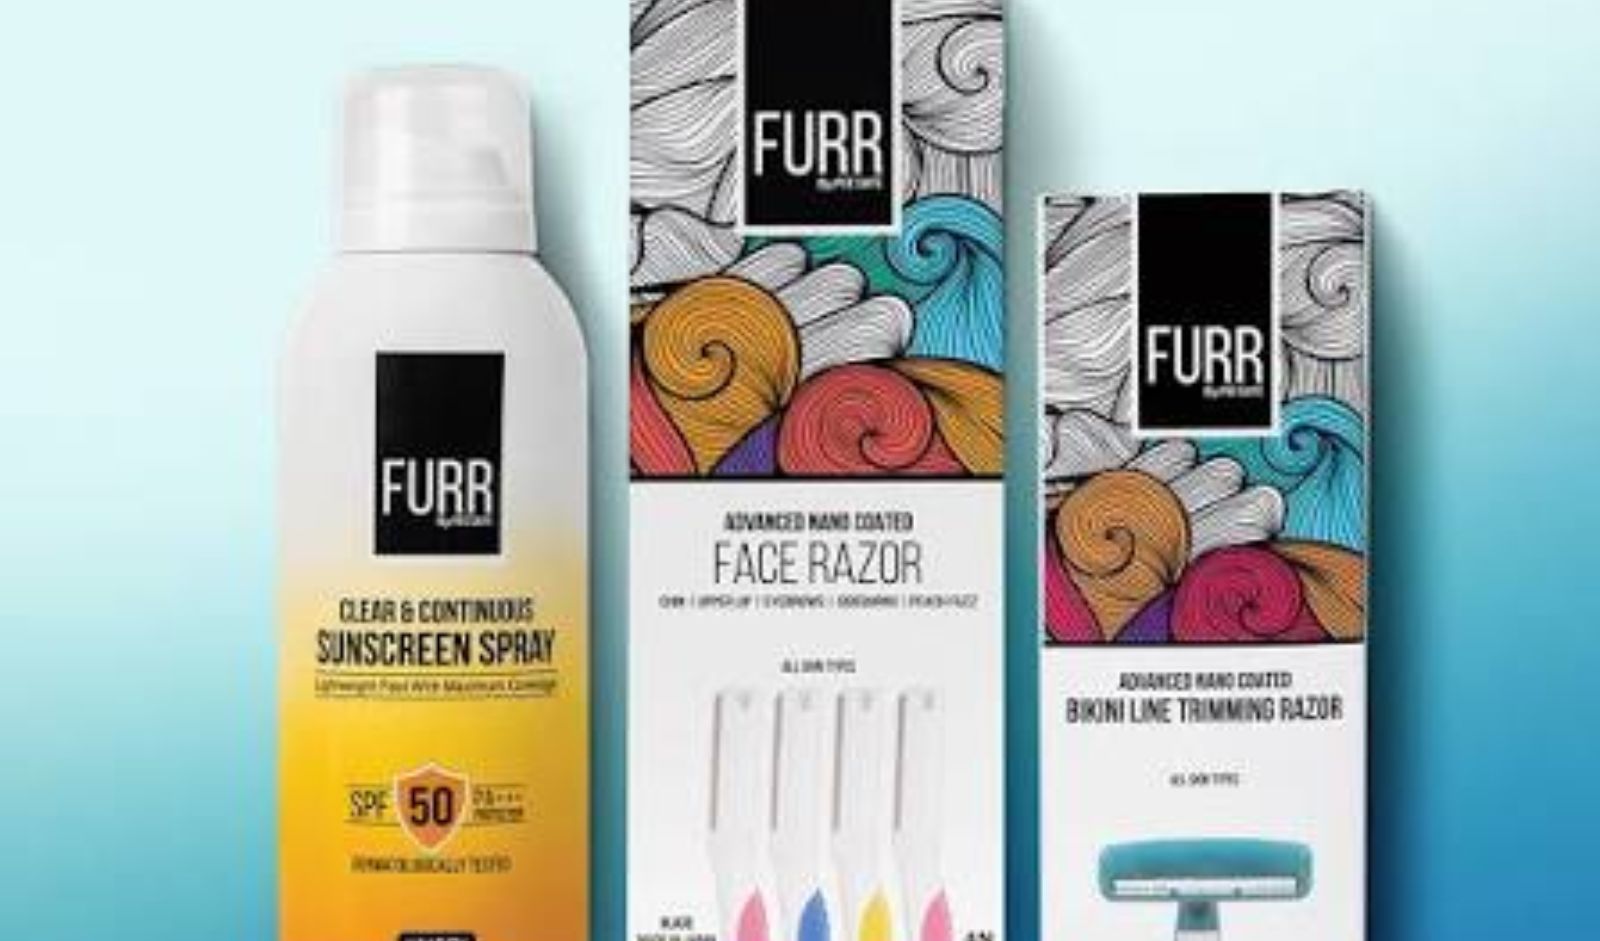
Festive preparation extends beyond the face to hair, body and everyday grooming. FURR by Pee Safe offers products across face care, body care, haircare, foot care and grooming, giving consumers options for a broader self-care routine.
As celebrations involve long days, social gatherings and time spent getting ready, a consistent grooming routine can help consumers feel fresh and comfortable. Face and body care can support daily cleansing and moisturization, while hair and foot care products can be incorporated into personal grooming before festive outings.
Why explore the brand: FURR offers a range of personal-care and grooming categories for consumers who want to cover more than just skincare in their festive preparation.
How to Build a Simple Festive Beauty Routine
A festive beauty routine does not need to involve an extensive collection of products. The key is to choose products suited to your skin type and grooming needs, and use them consistently.
- Start with cleansing: Use a gentle cleanser to remove dirt, oil and impurities.
- Focus on hydration: Apply a moisturizer suited to your skin type to help maintain skin comfort.
- Use sunscreen during the day: Choose a broad-spectrum sunscreen and reapply as directed, particularly when spending time outdoors.
- Prepare before makeup: Give skincare products time to settle before applying makeup. Avoid trying several unfamiliar products immediately before an important event.
- Include hair and body care: Choose suitable products for hair, body and foot care as part of your overall grooming routine.
- Keep the routine consistent: Avoid introducing multiple strong active ingredients or aggressive exfoliation just before celebrations, as these may irritate the skin.
Final Word
From accessible beauty essentials and skin-prep products to Ayurvedic-inspired personal care and nature-led formulations, Insight Cosmetics, FURR by Pee Safe, Suroskie, Ashpveda and Wildflower Naturals offer different ways to approach festive skincare and grooming.
The right choice depends on individual preferences, skin type and personal-care needs. By focusing on cleansing, hydration, sun protection and regular grooming, consumers can build a practical routine to carry them from Navratri celebrations through Karwa Chauth and the rest of the festive season.
FAQs
1. What is a good skincare routine for Navratri and Karwa Chauth?
A simple festive skincare routine includes cleansing, moisturizing and applying sunscreen during the day. You can add a serum or other targeted product based on your skin type and concerns. Follow a consistent routine rather than experimenting with several new products just before a celebration.
2. Which skincare and grooming brands can you explore for the festive season?
Insight Cosmetics, FURR by Pee Safe, Suroskie, Ashpveda and Wildflower Naturals are five brands to explore. Their portfolios cover different categories, including skincare, skin preparation, haircare, body care and everyday grooming.
3. How can you prepare your skin before festive makeup?
Start with a gentle cleanser and a moisturizer suited to your skin type. Apply sunscreen during the day and allow skincare products to settle before applying makeup. Avoid aggressive exfoliation or unfamiliar products immediately before an important event.
4. Which beauty products are useful for festive grooming beyond skincare?
Depending on your needs, useful additions may include haircare products, body moisturizers, foot-care essentials and fragrance. Choosing products you already know work for you can help keep your festive grooming routine simple and comfortable.
5. How do you choose the right skincare products for the festive season?
Choose products according to your skin type, concerns and ingredient preferences. Look for essentials that support cleansing, hydration and sun protection, and introduce targeted products gradually. If you have sensitive skin, patch-test new products before regular use.
If one were to look back to the beauty buyer about a decade ago, and compare her to the buyer today, one would feel that two different countries are being described. The consumer of yesterday’s India picked up whatever was available on the retail shelf and seldom looked past the packaging. On the contrary, today’s Indian buyer reads ingredient lists like fine print on a contract. This complete transformation, from passive assimilation to active curation, is the single biggest change that has reshaped this industry.
From Shopper to Scholar
Modern Indian beauty consumer behaves more like an amateur dermatologist than just a shopper. Courtesy the Millennials and Gen Z, who now contribute a major part of the category growth, buyers no longer respond to dime-a-dozen promises of glowing skin. They cross-reference formulations for specific actives, just as the previous generation checked nutrition labels. Ingredient literacy is the bare minimum expectation now, and interestingly, it is not a niche behaviour.
As a matter of fact, this scrutiny has paved the way for the evolution of the formula itself. We’re witnessing an appetite for products that multitask; a lip gloss infused with peptides, a foundation carrying a serum’s worth of actives. As consumers increasingly want colour cosmetics to do double duty as skincare, brands that continue to treat makeup and skincare as completely separate categories risk falling behind.
Trust Has Changed Hands
Celebrity endorsement, once the currency that sold everything from bath soaps to cosmetics in this country, has lost its monopoly. Today, discovery runs through peer networks and micro-influencers a lot more than through a popular face on a billboard. Platforms have built entire discovery engines around thousands of creators driving trend-led conversations every month, rewriting how trust gets built without much hullabaloo.
Not too surprisingly, this has changed how founders show up for their own brands. Buyers today place real value on founder-led narratives; visibility on platforms like Instagram and LinkedIn is not vanity, in fact, it is an indication of trust. Brands ready to place a real, accountable face behind their formulations are more likely to build a stronger bond with buyers than those hiding behind a logo. Authenticity has become a genuine competitive advantage, not a mere marketing checkbox.
The Ten-Minute Consumer
It is important to note that the most structurally disruptive shift has been witnessed in delivery expectations. From being a category that once operated on a three-day e-commerce wait, it is now increasingly flourishing, thanks to the ten-minute quick-commerce window. The myriad quick commerce platforms have not just moved logistics in top gear, but they have also brought about a paradigm shift in the beauty purchasing behaviour. No longer a considered, monthly stock-up, but high-frequency and occasion-led, it is now closer to how people buy groceries than how they used to buy skincare.
Of course, this has real operational consequences. Brands are re-engineering supply chains especially to cater to quick-commerce hubs in metros like Mumbai, Delhi-NCR, and Bengaluru, so impulse-level demand can be addressed in the moment it is felt. Speed is no longer a differentiator; it is table stakes.
Digital Discovery, Physical Trust
It must also be mentioned that digital-first does not mean digital-only. While the initial wave of D2C beauty in India was built almost entirely on online storefronts, today’s consumer considers a brand’s physical footprint as a badge of credibility. The journey is genuinely hybrid; the discovery happens on Instagram, research takes places on the brand website, but the final layer of trust often still comes from a physical touchpoint: an experience centre, a consultation, a chance to see and feel the product before committing. Not surprising that even the biggest digital-native players have aggressively moved into offline retail to capture precisely this kind of conversion.
Beyond the Metros
The ultimate, and perhaps the most exciting shift, is geographic. The centre of gravity in Indian beauty consumption has moved well past the top metros, and how! Tier-2 and tier-3 markets are now the real growth engines, powered by regional-language internet access, rising disposable incomes, and an appetite for global beauty rituals that mirrors the biggest cities. Interestingly, consumers in what is increasingly called “Bharat” are not a diluted version of the metro buyer. Their aspirations are just as informed and equally demanding as well.
What This Means for Founders
Collectively, these shifts describe a consumer who has fundamentally outgrown the D2C playbook most beauty brands were originally built on. They want proof, not promises. They want a real person behind the brand, not a faceless logo. They want their product in minutes, not days. And they want all of this whether they are browsing from Mumbai, Delhi, Bengaluru, or from a small town a couple of states away.
So, building for them is not an option anymore. It is the only way forward.
Authored By
Swagatika Das, CEO & Co-Founder, Nat Habit
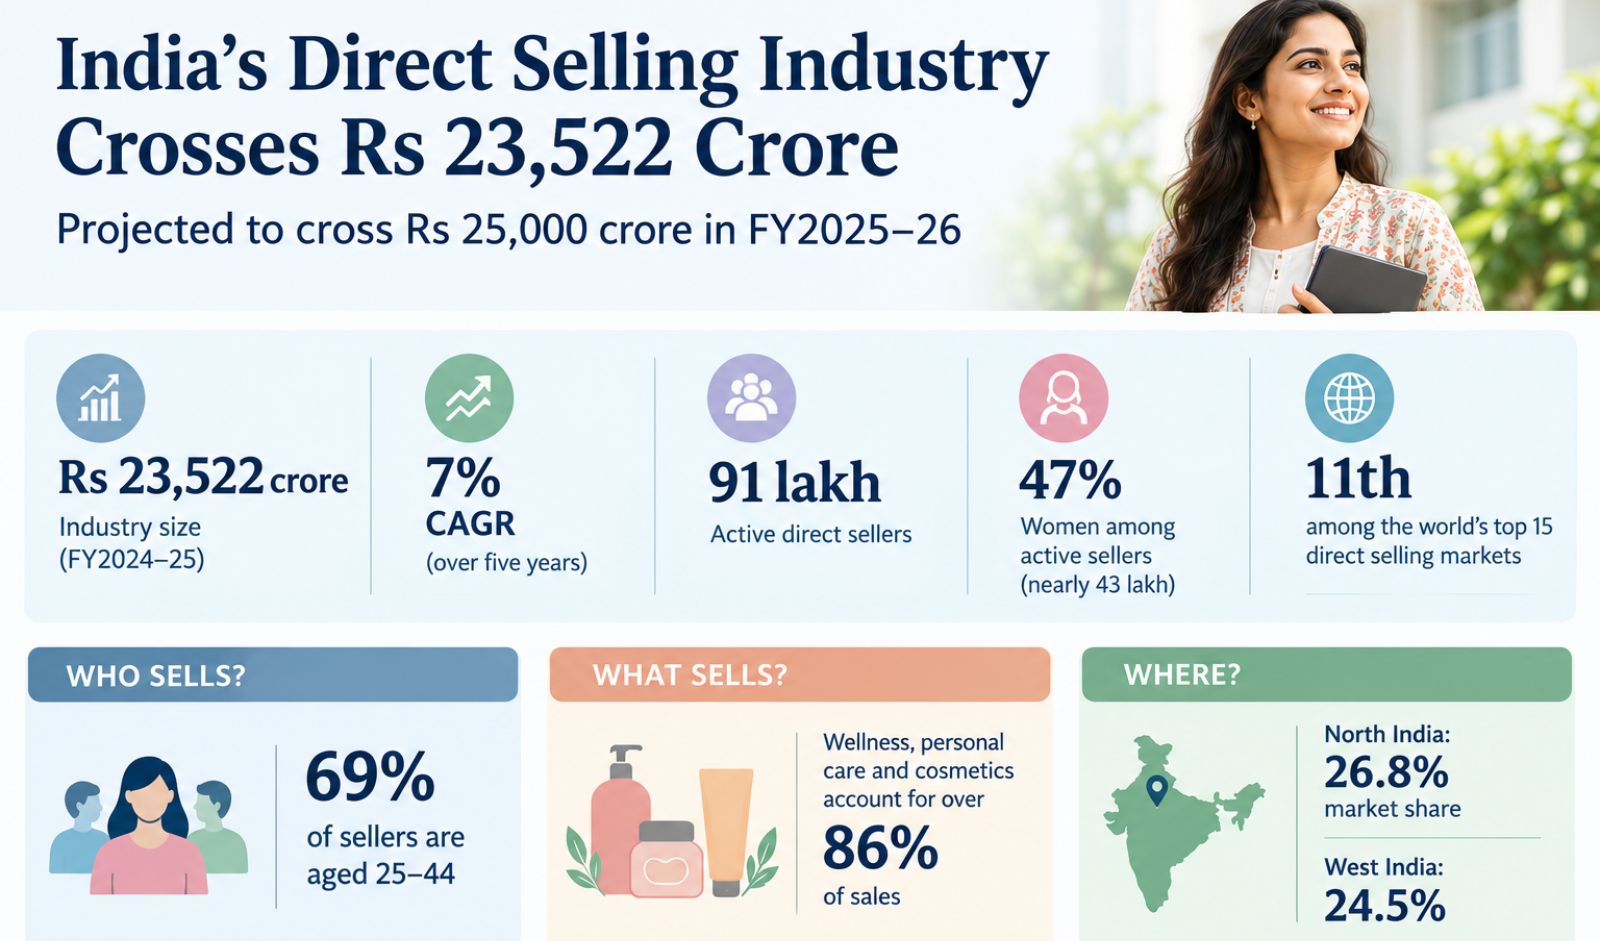
India’s direct selling industry is emerging as a significant source of livelihood and entrepreneurial opportunity. Valued at Rs 23,522 crore in FY2024–25, the industry recorded a 7 percent compound annual growth rate (CAGR) and is projected to cross Rs 25,000 crore in FY2025–26, according to the ADSEI Direct Selling Industry Report 2024–25, released in partnership with Kantar. India ranks 11th among the world’s top 15 direct selling markets, with wellness, personal care and cosmetics together contributing more than 86% of industry sales.
The industry currently has more than 91 lakh active direct sellers, with women accounting for 47% of the workforce. The findings highlight the sector’s growing role in providing income opportunities, particularly for women and individuals seeking flexible avenues for self-employment.
The report was released at Bharat Mandapam, New Delhi, and examines the industry's market size, seller demographics, income patterns, product categories and evolving regulatory environment.
Women Account for 47% of Active Direct Sellers
Women remain a significant part of India’s direct selling workforce, accounting for nearly 43 lakh of the 91 lakh active sellers. According to the report, the sector’s relatively low capital requirements, flexible working hours and lack of formal qualification barriers make it accessible to individuals across different socioeconomic backgrounds.
These characteristics can be particularly relevant for women in semi-urban and rural markets, where direct selling offers an avenue to earn an independent income alongside existing responsibilities.
The findings also connect the sector’s livelihood potential with broader conversations around women-led development and financial inclusion. For many participants, earnings can contribute to household expenses, education, healthcare and savings.
Gautam Bali, Patron, ADSEI, said the industry’s contribution extends beyond its overall revenue, pointing to the number of people using direct selling as a source of livelihood and the participation of women in smaller towns and villages.
He also highlighted the need for stronger training, governance and consumer-focused practices to help sellers establish sustainable businesses and remain active in the sector.
Young Workforce and Income Opportunities Shape the Industry
The report indicates that around 69% of active direct sellers are between 25 and 44 years old, underlining the participation of working-age individuals in the sector.
It also finds that more than 32% of sellers report consistent month-on-month income from direct selling. The data points to the sector’s potential as an income-generating activity, although earnings and business outcomes can vary across individuals.
Beyond selling products, onboarding and training programmes can help participants develop skills in communication, customer engagement, sales and basic financial management. These capabilities can also support individuals looking to build small businesses or explore other entrepreneurial opportunities.
However, seller retention remains an area for improvement. Bali noted that some participants leave before their businesses become established, highlighting the importance of better training, governance and consumer trust in building long-term participation.
Wellness and Personal Care Drive More Than 86% of Sales
Wellness, personal care and cosmetics collectively account for more than 86% of the direct selling industry's total sales, according to the report.
The concentration of sales in these categories reflects the sector’s reliance on products linked to regular consumer use and household purchasing needs. For direct selling companies, these segments also place emphasis on customer relationships, product awareness and repeat purchases.
Geographically, North India is the largest contributing region, accounting for 26.8% of the market, followed by West India at 24.5%.
The regional distribution highlights the importance of markets beyond the country’s largest metropolitan centres in supporting the industry’s overall business. Direct selling’s presence across diverse locations also creates opportunities for companies to reach consumers through individual sellers rather than relying exclusively on conventional retail outlets.
Regulatory Framework Brings Focus on Compliance and Consumer Trust
The Consumer Protection (Direct Selling) Rules, 2021, are identified in the report as an important milestone in the formalization of the sector. The rules established a more defined regulatory framework for direct selling entities and their operations, placing greater emphasis on consumer protection and compliance.
According to ADSEI, sellers surveyed for the report expressed positive views about the influence of existing policies, public perception of direct selling and the industry's growth prospects over the next two years.
Dr. Sanjeev Kumar, President, ADSEI, said the industry supports the broader objectives of self-employment, skilling and women-led development.
“This report establishes, with credible quantified and qualitative data, what Direct Selling substantively contributes to India: at the core of it is livelihoods for more than 91 lakh people, nearly half of them women, built on the spirit entrepreneurship,” he said.
Kumar added that ADSEI would continue to work with the government to strengthen compliance and consumer trust.
For the industry, maintaining consumer confidence will remain important as the sector expands. Transparent business practices, clear product information, appropriate seller training and responsible consumer engagement are central to building credibility and encouraging sustained participation.
India Ranks 11th Among the World’s Top Direct Selling Markets
India’s position as the 11th-largest direct selling market globally provides an international benchmark for the sector’s scale. With the domestic industry valued at Rs 23,522 crore in FY2024-25 and projected to exceed Rs 25,000 crore by the next fiscal, the report points to further growth potential.
The sector’s future development will depend not only on increasing sales but also on the quality and sustainability of the livelihoods it supports. Seller retention, training, governance and compliance are likely to remain important considerations as companies seek to expand their reach.
The report’s estimates were developed through a three-stage methodology. ADSEI and Kantar built a universe of direct selling companies using industry sources, company disclosures and Ministry of Corporate Affairs filings, and analysed up to seven years of financial and operational data.
The estimates were subsequently assessed through in-depth stakeholder interviews, a quantitative survey of direct sellers and expert consultations. The research also considered business-as-usual, optimistic and pessimistic scenarios.
As India’s direct selling industry moves towards the Rs 25,000 crore mark, its performance will be measured by both market expansion and its ability to provide more sustainable income opportunities while strengthening consumer confidence and regulatory compliance.
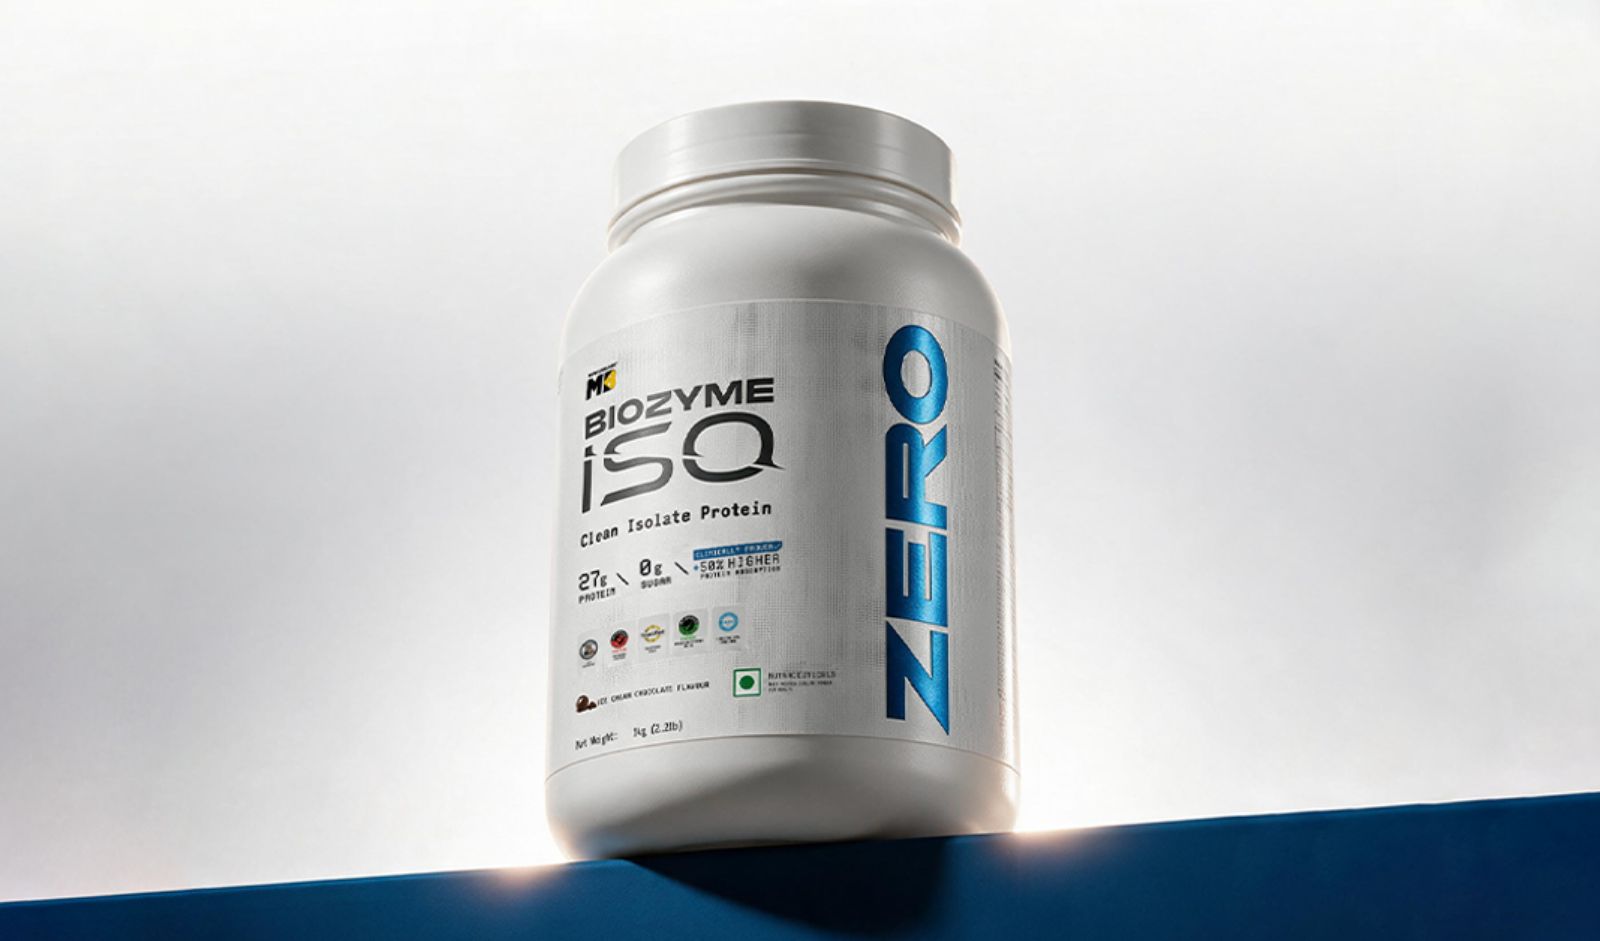
India, 9 October 2026: For years, the premium whey protein isolate market in India has been influenced by a widely held consumer perception: imported products are inherently superior to Indian alternatives. MuscleBlaze is looking to challenge that belief with Biozyme Iso Zero, shifting the conversation towards scientific evidence, product quality and independent validation.
Biozyme Iso Zero delivers 27g of protein per scoop from 100% whey protein isolate, with zero added sugar and zero artificial sweeteners. It has been reformulated with stevia in place of artificial sweeteners, is 99% lactose-free, and contains five core ingredients: whey isolate, MB EnzymePro, steviol glycosides, bromelain and lecithin. There are no added fillers or gums, and the pack ships with a compostable scoop.
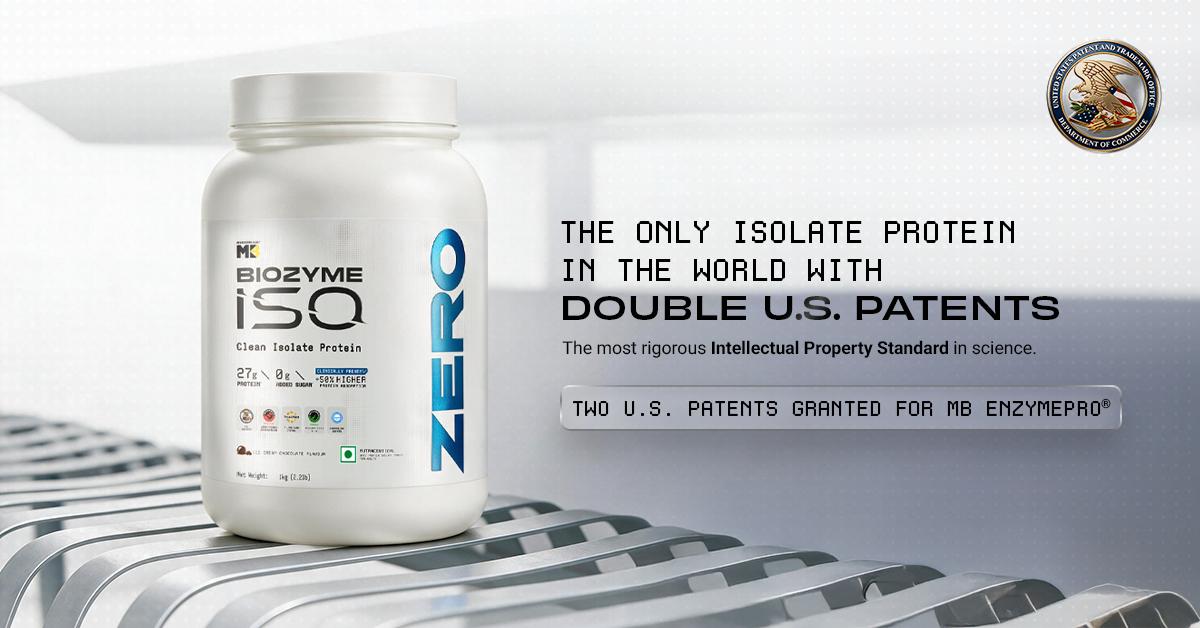
At the centre of the proposition is MB EnzymePro, an enzyme technology designed to break whey protein molecules into smaller peptides. The product has been clinically evaluated for protein absorption and demonstrated 50% higher protein absorption than regular whey, according to the company's clinical assessment. The technology is supported by two US patents, underscoring the company's focus on proprietary innovation in sports nutrition.
Biozyme Iso Zero has also undergone blind testing at independent laboratories in the United States, the United Kingdom and India, covering purity, label accuracy, heavy metals, amino spiking and banned substances. It carries credentials from Informed Protein USA, Informed Choice UK, Trustified Gold, Asia and Labdoor USA. In a market with a growing range of protein supplements and increasingly varied product claims, the company believes multi-market testing offers consumers a clearer basis for comparison than brand origin alone.
The move comes as India's sports nutrition market evolves beyond conventional parameters such as protein content, pricing and flavour. Consumers are increasingly evaluating supplements based on formulation, product quality and the evidence supporting performance-related claims.
Commenting on the development, Kaustuv Paliwal, Senior Vice President at Bright LifeCare, the parent company of MuscleBlaze said, "The premium sports nutrition category needs to move beyond the perception that international origin automatically translates into superior quality. At MuscleBlaze, we believe innovation must be backed by research, rigorous testing and evidence that consumers can evaluate. Our focus is on building products that compete on their merits and demonstrate the capabilities of Indian sports nutrition innovation."
For MuscleBlaze, the ambition is to move the category conversation from imported versus Indian to perceived versus proven. As consumer expectations evolve, the company believes the next phase of growth in premium sports nutrition will be shaped by brands that can demonstrate the science and quality behind their products.
About MuscleBlaze
MuscleBlaze is an Indian sports nutrition brand focused on developing science-led nutrition products for consumers across fitness, performance and active lifestyles. Its portfolio spans protein, creatine and sports nutrition products, with an emphasis on product innovation, quality and consumer trust.
The rise of online marketplaces has changed how India shops, but it has not made physical retail irrelevant. In categories such as fashion and footwear, where fit, comfort and personal preference decide the purchase, customers still want to see and try a product before they buy it. Specialty stores, malls and brand outlets continue to matter.
For digital-first brands, moving into physical retail is less an expansion decision than a natural next step. Online gives you speed, reach and customer data. Offline brings the human element back into buying: the ability to try something, ask questions and experience the brand.
Two customers, one purchase
This matters more in kids' footwear than almost anywhere else, because every purchase involves two people. The parent decides and pays. The child wears the product and has firm opinions about it.
Watching children try shoes in stores, it is obvious they do not respond to technical features alone. They respond to movement: how it feels to run in, whether they can put the shoe on themselves. The parent standing beside them is assessing something entirely different, which is durability, fit and whether this is worth the money. Both have to land or the sale does not happen. That single observation can shape decisions as specific as closure systems and colour palettes, and these are insights that are difficult to reach from analytics alone.
Buyer behaviour is also shifting in ways that many brands may not predict. Fathers are increasingly becoming active participants in children's footwear purchases, while girls represent a significant share of young footwear consumers. Understanding these shifts is important for brands as they think about product, communication and retail experience.
Some products have to be held
Trust is the other reason physical retail earns its place. Parents want to be certain that what they are buying is comfortable, well made and right for growing feet.
For children's footwear, that is not a general argument, it is a specific one. Features designed around growing feet, comfort and adaptability can sound like marketing claims when communicated only on a screen. Put the product in a parent's hands and let them experience how it works, and the conversation can change in seconds. A screen cannot always do that. A store can.
Start with where the customer already is
Moving offline brings real estate commitments, inventory planning and channel alignment, and all of it puts pressure on a growing brand. The most expensive mistake is to judge expansion by visibility or store count.
High mall footfall alone does not necessarily carry a children's brand. Family catchment, the brands around the store, the capability of the staff and the quality of the fit conversation can matter far more than headline traffic. Brands need to build the training, merchandising and inventory systems before expansion works as a system rather than a series of one-off bets.
The better first question is simpler. Where is the customer already?
A brand's online business can answer that. Order data can show consistent demand in cities well before a physical presence is established, helping shape a retail map based on genuine demand rather than prestige addresses. Sales locations, repeat purchases, return patterns and feedback can all tell you where that demand already exists.
You also do not need to begin with standalone stores. Alongside exclusive outlets, kiosks, shop-in-shop formats and large-format retail can help a brand test a market and build presence without heavy real estate commitments from day one. The honest caveat is that these formats are not equivalent. A full store can carry the entire fit conversation. A kiosk gives you reach but cannot always do that, and brands need to recognise the difference between each touchpoint.
Connect the two, do not run them separately
The next step is to stop treating physical and digital as two businesses. An online customer should be able to find the nearest store, check availability or collect in person. Someone who discovers the brand in a store should be able to continue online through easy reordering, support and loyalty.
In footwear, that loop is the whole model. A parent finds a brand on social media, comes into a store to be sure about fit, buys there, and then reorders online without walking in again. The journey is already omnichannel even when a single transaction is not.
Stores can also hold relationships that have nothing to do with a transaction. Take-back programmes can bring parents back into stores with outgrown shoes, which can then be revived and passed on to children who need them through NGO partners. Such initiatives can create engagement and repeat visits without relying entirely on advertising or discounting.
What the numbers say
The clearest evidence that the two channels reinforce each other is acquisition cost. As offline scales, it can support customer discovery and reduce the dependence on paid social, which has become more expensive across the industry. Retail does the fit discovery, and a meaningful share of the repeat purchasing can then happen online.
India's retail market is moving in the same direction. Rising purchasing power, sharper awareness of product quality and ergonomics, and a growing willingness to pay for a real difference are pushing consumers past purely functional buying.
For a brand like ours, the opportunity is not to open more stores. It is to use physical retail to prove what makes the product different, and digital to extend that relationship over years.
Digital offers reach, convenience and data. Physical retail offers experience, interaction and trust. In kids' footwear, where the product has to satisfy both the parent and the child, getting that balance right is what separates a retail business that is bigger from one that lasts.
Authored by:
Satyajit Mittal, Founder & CEO, Aretto
Quitting smoking is difficult largely because nicotine dependence can trigger cravings and withdrawal symptoms when tobacco use stops. Nicotine replacement therapy or NRT is one evidence-based approach used to provide controlled nicotine without exposure to the harmful chemicals produced by burning tobacco. The World Health Organization recommends NRT among the pharmacological options that can support adults who want to quit tobacco.
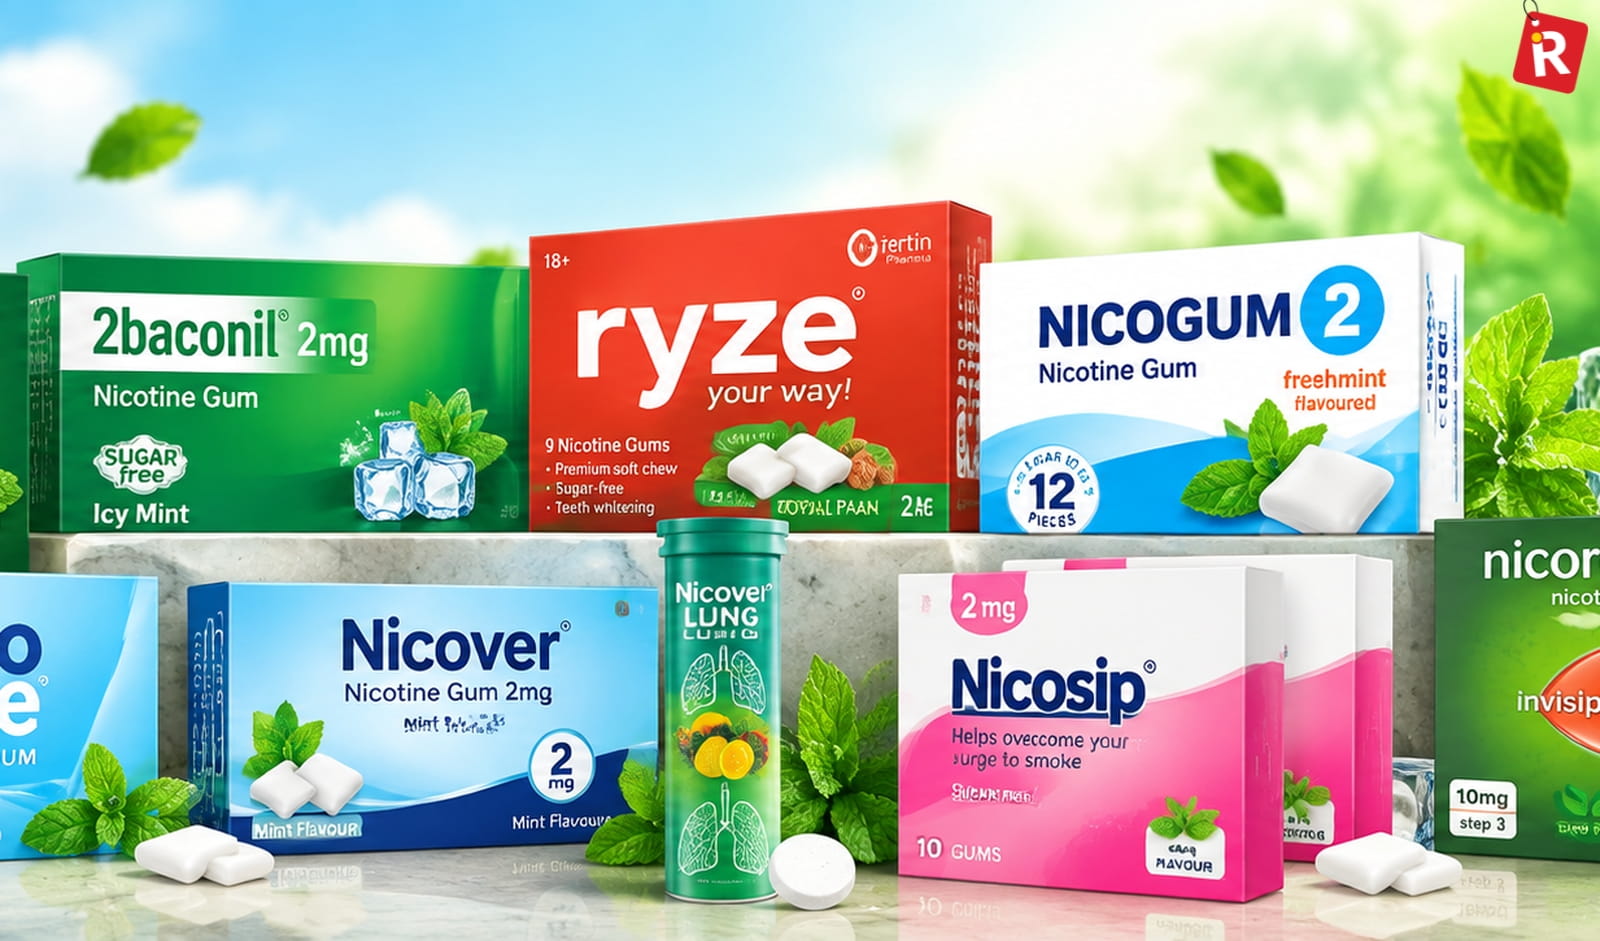
In India, the nicotine gum category has expanded beyond a few familiar products. Consumers can now find brands such as Nicotex, 2baconil, Ryze, Nicogum, Nicosure, Nicover and other nicotine replacement products through pharmacies and online healthcare platforms. Current listings show multiple strengths, flavours and pack sizes across the category.
This article looks at the Top 8 Nicotine Gum Brands for Smoking Cessation in India, focusing on their market presence, available formulations and positioning. The list is not a ranking of medical effectiveness. Nicotine gum contains an active drug, and the appropriate strength and usage should be selected according to the product instructions and, where appropriate, advice from a doctor or pharmacist.
Understanding Nicotine Replacement Therapy in India
Nicotine gum is a short-acting form of NRT. It provides a controlled amount of nicotine to help manage cravings and withdrawal while a person works towards stopping tobacco use. Unlike cigarettes, NRT does not deliver nicotine through tobacco smoke. WHO includes nicotine gum, patches and other NRT formats among pharmacological treatments that can support tobacco cessation.
The category is also becoming more accessible through pharmacies, e-pharmacies and quick-commerce platforms. Current Indian pharmacy listings show nicotine gums across brands, strengths and flavours, making product discovery considerably easier than it was in the past.
Read more: Top 10 Sports T Shirts Brands Redefining India’s Everyday Activewear
Top 5 Cigarette Brands Shaping India's Tobacco Industry
Top 8 Watch Brands in India Redefining Everyday Luxury
Top 8 Nicotine Gum Brands in India
1. Nicotex
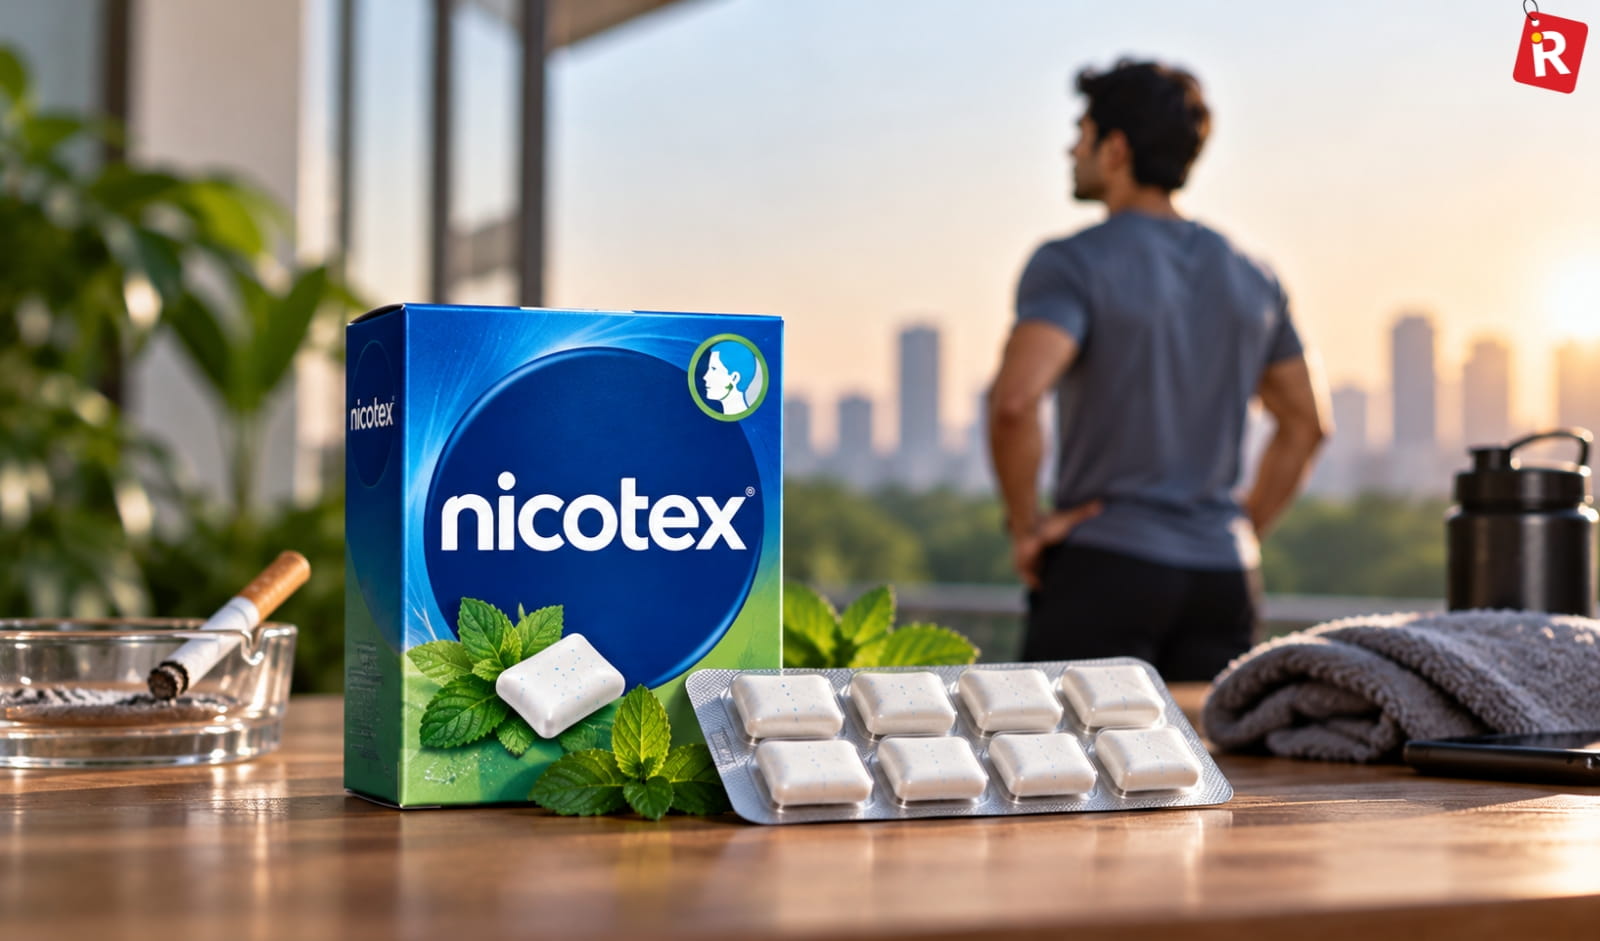
Nicotex is one of the most visible nicotine gum brands in India's smoking-cessation category and is marketed by Cipla Health. Its range includes 2mg and 4mg nicotine gums, with flavours including Mint Plus, Paan, Cinnamon, Ultra Mint and Fruit Burst. The brand positions its products around nicotine replacement therapy and a structured 12-week approach to reducing nicotine dependence. Nicotex is also widely represented across pharmacy and digital-commerce channels. Its broad flavour and pack-size portfolio makes it one of the most recognisable names for consumers searching for nicotine gum in India.
2. 2baconil
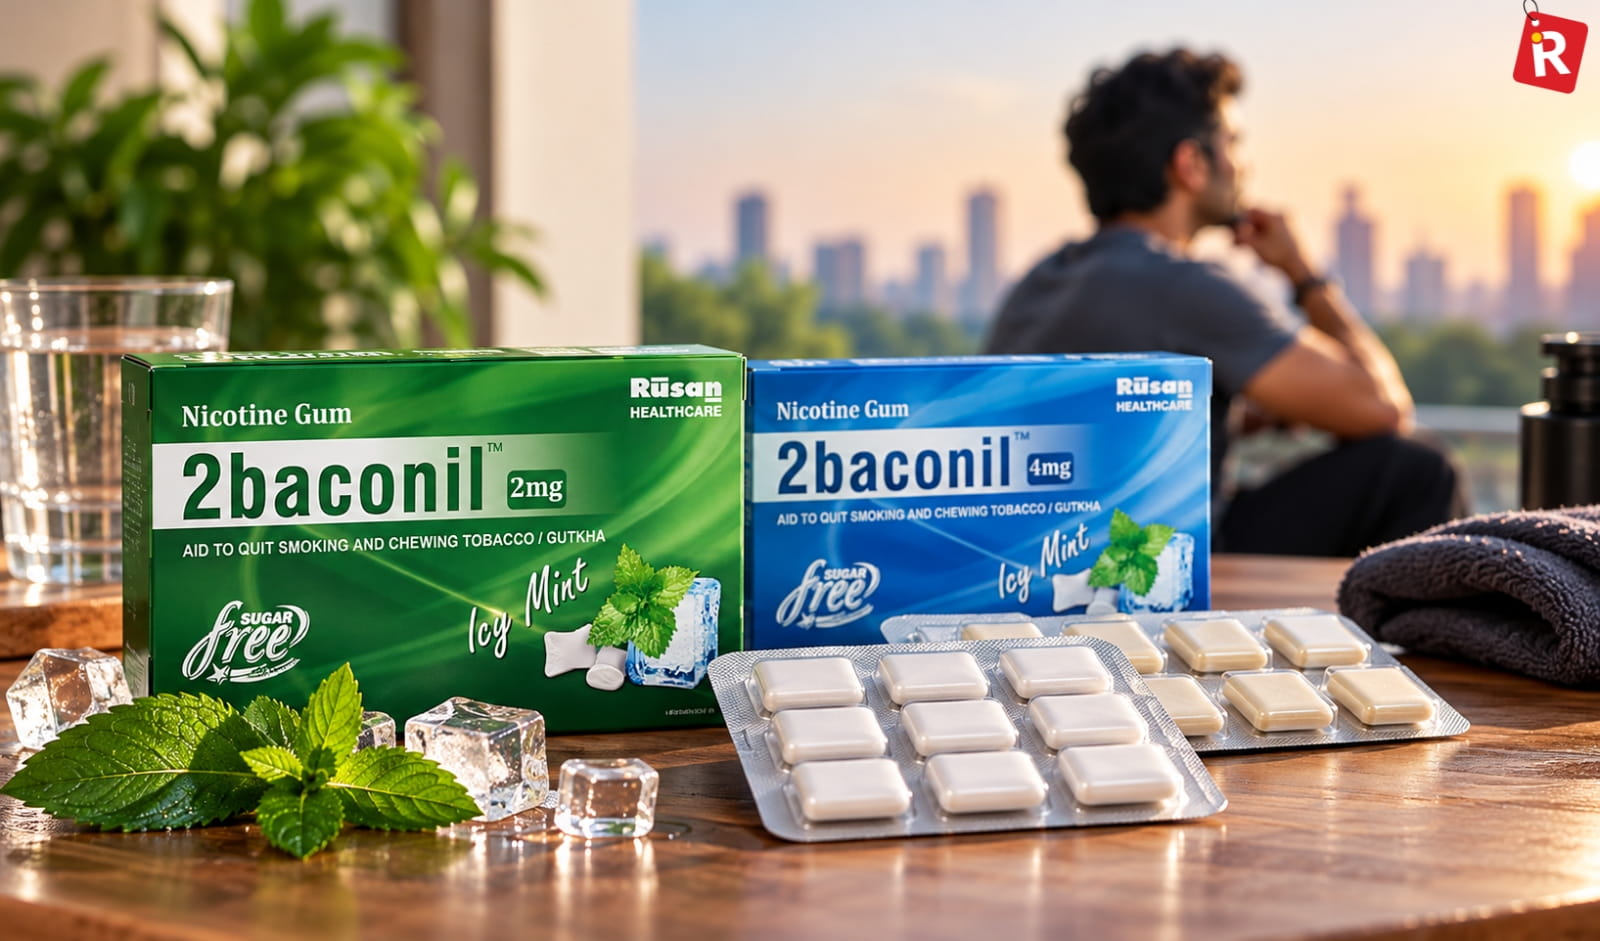
2baconil is another established NRT brand available in India, with nicotine gums offered in 2mg and 4mg strengths. Pharmacy listings show the brand in sugar-free formats, including Icy Mint, alongside its wider smoking-cessation portfolio that includes nicotine patches. The brand is marketed by Rusan Healthcare and is available through major online pharmacy channels. Its presence across both gum and patch formats gives consumers access to different NRT options within the same brand ecosystem. For the Indian smoking-cessation market, 2baconil represents one of the established alternatives to Nicotex.
3. Ryze
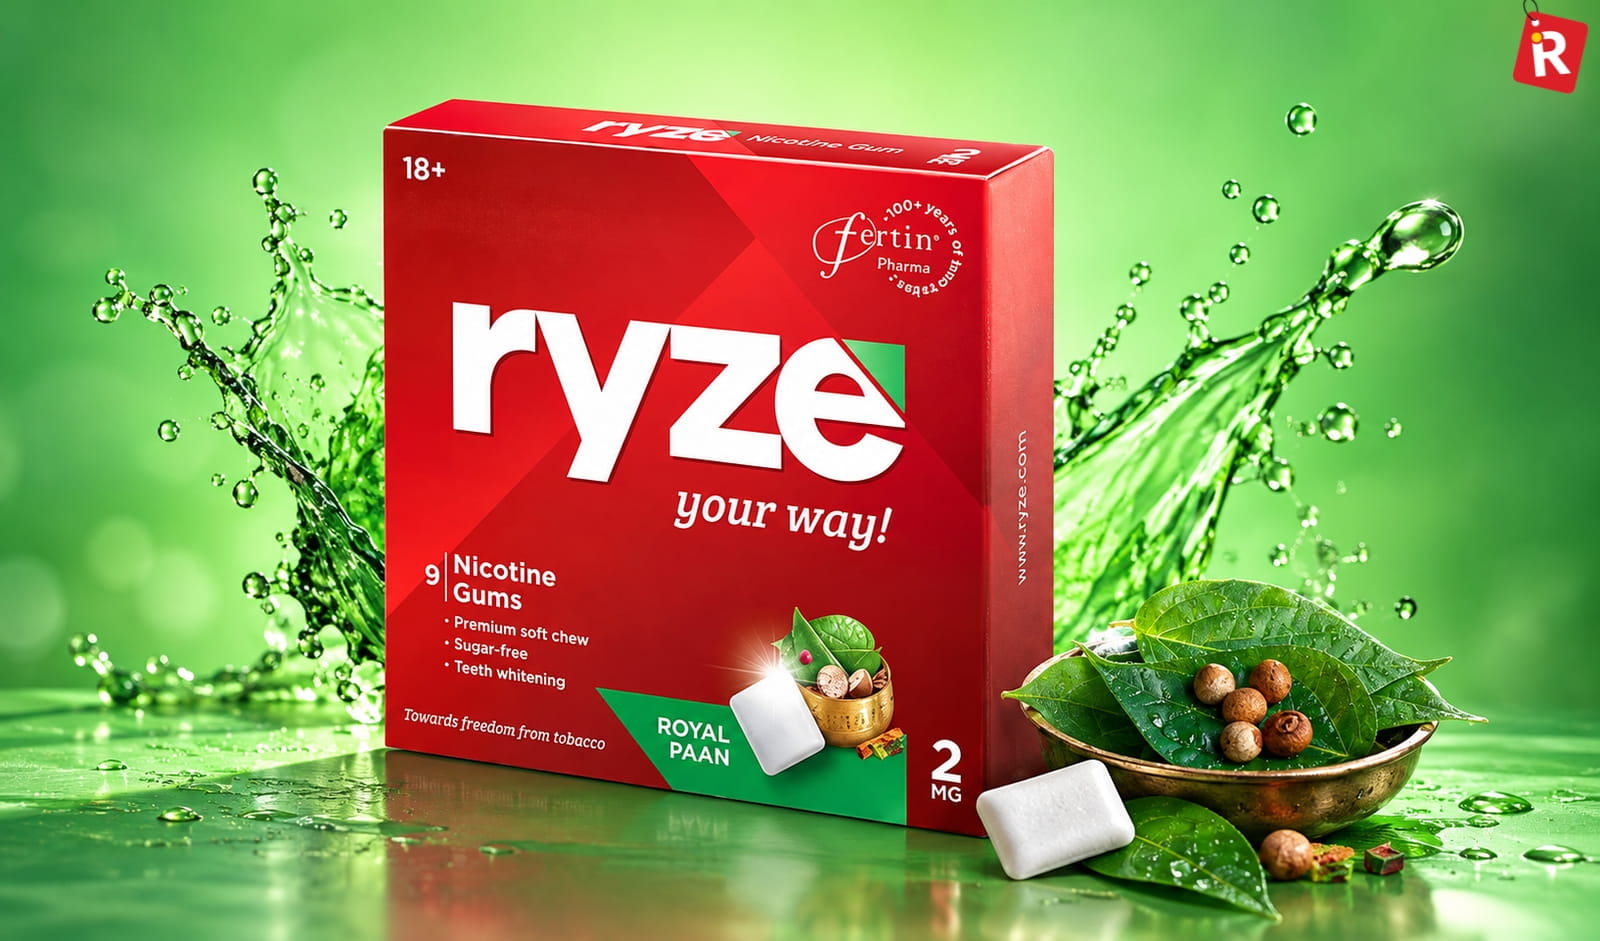
Ryze has added a more flavour-led proposition to India's nicotine gum category. Its portfolio includes 2mg and 4mg gums in flavours such as Frosty Mint, Royal Paan, Fruit Blast, Fresh Fennel, Pudina Punch and Paan Masala. The brand is widely listed across pharmacy and quick-commerce platforms, reflecting the increasing digital availability of smoking-cessation products. Ryze is also noteworthy from a market perspective because research has identified it among newer nicotine products associated with tobacco-industry companies. Tobacco Induced Diseases Consumers should therefore distinguish brand availability from clinical suitability and consult healthcare professionals when needed.
4. Nicogum
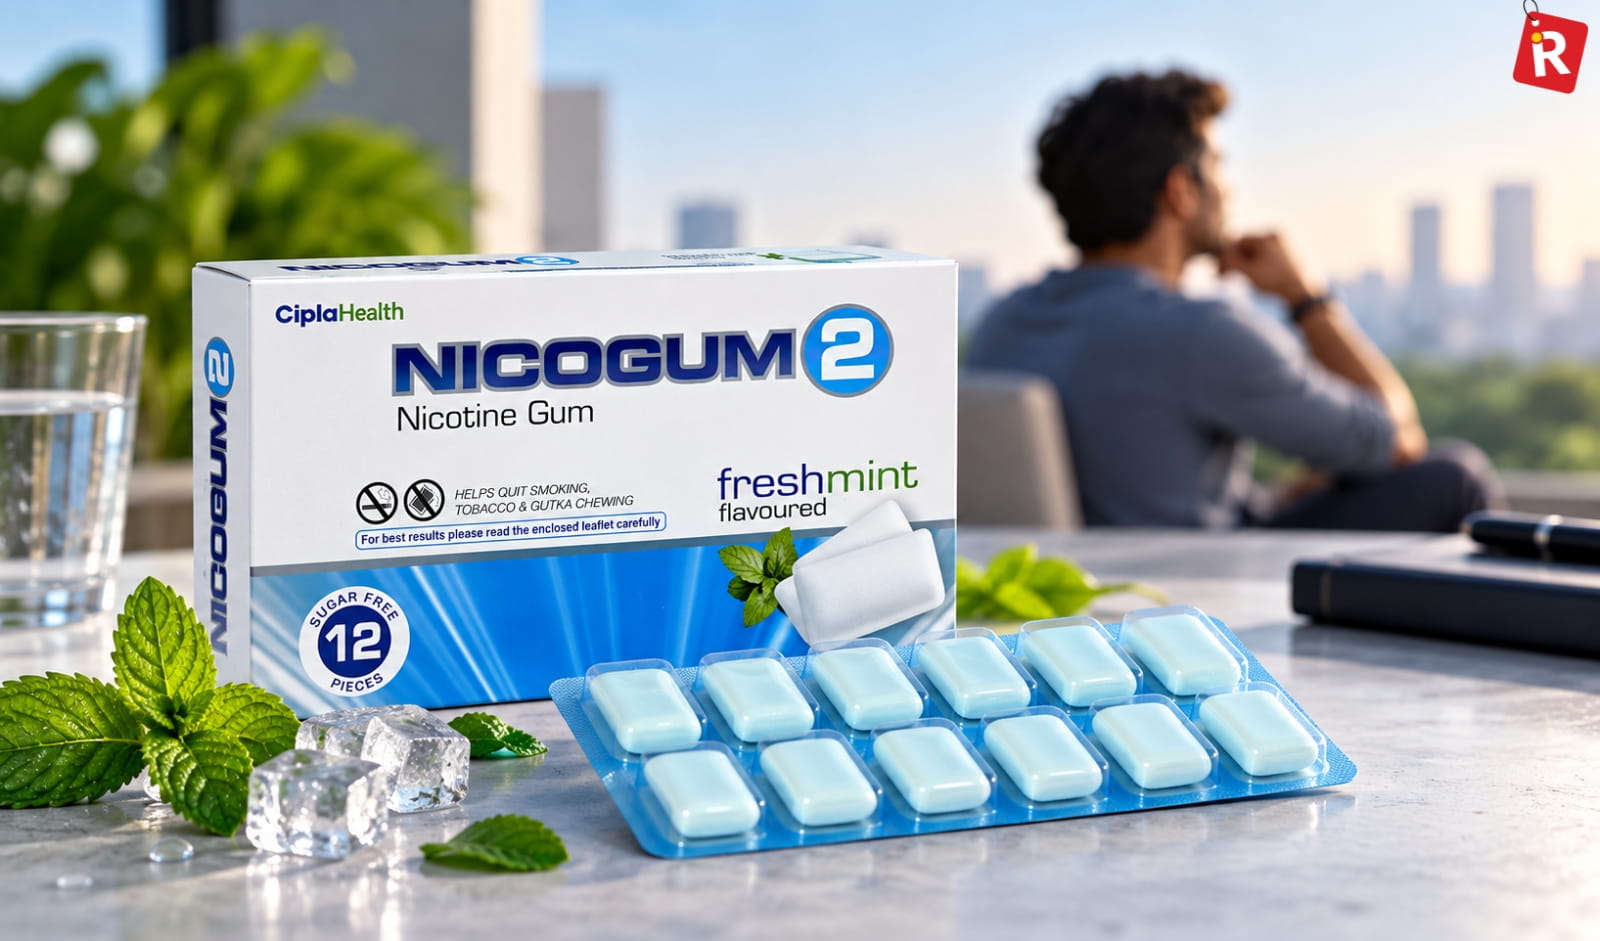
Nicogum is another nicotine replacement gum available to Indian consumers, with products listed in 2mg and 4mg strengths. Pharmacy listings identify Nicogum as a smoking-cessation product containing nicotine and show formats such as Freshmint and sugar-free variants.The brand is available through pharmacy channels alongside other established NRT products. Nicogum's positioning is relatively straightforward: provide nicotine in gum form to help manage cravings and withdrawal associated with stopping tobacco. Its availability gives consumers another option when comparing nicotine gum brands based on formulation, strength, flavour, price and accessibility.
5. Nicosure
Nicosure is an ITC-marketed nicotine replacement brand available in India. Its range includes 2mg and 4mg nicotine gums, alongside nicotine lozenges. Current product listings describe Nicosure gum as nicotine polacrilex-based NRT designed to provide a controlled dose of nicotine and help reduce cravings associated with stopping tobacco use. The brand also offers flavour options such as Spearmint and Paan Bliss. Its presence across online pharmacies and quick-commerce platforms illustrates how nicotine replacement products are increasingly becoming part of India's digitally accessible healthcare retail market.
6. Nicover
Nicover represents a newer consumer-facing approach to nicotine replacement gum. Its current offering centres on sugar-free 2mg nicotine gum in a mint flavour, positioned around managing cravings and gradually reducing nicotine dependence. Unlike some of the larger pharmacy-led brands, Nicover places considerable emphasis on direct consumer education and guided quitting plans through its digital platform. This reflects a wider shift in healthcare retail, where consumers increasingly discover products online and expect supporting information alongside the product itself. Nicover therefore adds a digital-first dimension to India's evolving nicotine gum category.
7. Nicosip
Nicosip is a nicotine replacement gum marketed by Leeford Healthcare and available in 2mg and 4mg formulations. Current pharmacy listings identify Nicosip as an NRT product used for smoking cessation and nicotine withdrawal, with products available in formats such as mint-flavoured sugar-free gum. The brand is also listed in pharmaceutical product portfolios alongside other nicotine replacement products. For consumers researching nicotine gum brands in India, Nicosip represents another pharmacy-market option where strength, formulation and professional guidance can be considered before use.
8. Nicorite
Nicorite is another nicotine gum brand available in India's pharmaceutical market, with 2mg and 4mg variants listed by its manufacturer and pharmaceutical suppliers. Its inclusion highlights the breadth of India's NRT market, where several brands operate beyond the most visible consumer names. As with other nicotine gums, the relevant consideration is not simply brand recognition but the nicotine strength, usage instructions, individual tobacco-use pattern and any medical considerations. Consumers should follow the product label and seek advice from a doctor or pharmacist when uncertain.
Why Nicotine Gum Is Part of India's Smoking Cessation Market
Nicotine gum occupies an important position within NRT because it provides a short-acting form of nicotine that can be used to address cravings as they occur. WHO's latest tobacco-cessation guidance recommends NRT as one of the pharmacological options for adults attempting to quit tobacco. It also notes that combining a nicotine patch with a short-acting NRT such as gum can be an option for some people.
This does not mean every smoker needs nicotine gum or that one brand is universally better than another. The appropriate approach depends on factors including tobacco consumption, nicotine dependence, previous quit attempts and individual health considerations.
Explore more: Top 5 Cookware Brands to Watch for Modern Indian Kitchens
5 Best Instant Coffee and Tea Brands in India 2026 for Daily Use
Top 5 Trimmer Brands for Men in India 2026
What Consumers Should Check Before Choosing Nicotine Gum
Consumers searching for the best nicotine gum in India should look beyond flavour and price.
Nicotine strength
Different products are available in different strengths, commonly including 2mg and 4mg. The appropriate strength depends on the individual's nicotine use and the product's instructions. For example, Nicotex states that its 2mg and 4mg products are intended for different levels of cigarette consumption.
Product instructions
Nicotine gum is not used exactly like conventional chewing gum. Nicotex, for example, instructs users to chew slowly until the nicotine taste appears and then park the gum between the cheek and gum.
Flavour and format
Mint, fruit, paan, cinnamon and other flavours are now available across the category. Flavour preference can influence how comfortable consumers find the product during a quitting programme.
Professional advice
Nicotine gum is a medicine containing nicotine and can cause side effects or be unsuitable in certain circumstances. Product information and healthcare advice should be considered before use.
Nicotine Gum and the Changing Healthcare Retail Landscape
The availability of nicotine gums through pharmacies, e-pharmacies and quick-commerce platforms reflects a wider change in healthcare retail.
Major platforms currently list multiple NRT brands, including Nicotex, 2baconil, Ryze, Nicosure and Nicogum. This makes comparison easier but also increases the importance of accurate product information.
For healthcare retailers, the category requires particularly responsible merchandising. Consumers need clear information about nicotine strength, intended use, warnings, prescription status where applicable and professional guidance rather than aggressive promotional messaging.
What the Nicotine Gum Category Means for Retailers
The smoking-cessation category has several characteristics that distinguish it from conventional FMCG.
Availability matters: Consumers experiencing cravings may value convenient access.
Information matters: Product pages should clearly communicate strength, formulation and directions.
Responsible merchandising matters: Nicotine replacement products should not be positioned like ordinary confectionery.
Pharmacy trust matters: Healthcare professionals can play an important role in helping consumers understand appropriate NRT use.
As digital healthcare retail continues to grow, brands that combine accessibility with clear, evidence-based consumer information are likely to have an advantage.
The Future of Nicotine Replacement Products in India
India's nicotine replacement category is becoming more diverse, with established pharmaceutical brands competing alongside newer digitally positioned products. The availability of multiple strengths, flavours, gum formats, patches and lozenges gives consumers more choices within NRT.
At the same time, the category requires careful communication. WHO's tobacco-cessation guidance places NRT within a broader quitting strategy that can include behavioural support and other evidence-based interventions.
For brands and retailers, the long-term opportunity is therefore not simply selling more nicotine gum. It is making evidence-based smoking cessation support easier to understand and access.
Conclusion
The Top 8 Nicotine Gum Brands for Smoking Cessation in India include Nicotex, 2baconil, Ryze, Nicogum, Nicosure, Nicover, Nicosip and Nicorite.
The category is evolving through wider pharmacy availability, digital commerce, multiple strengths and flavour choices. At the same time, nicotine gum should be viewed as a nicotine replacement medicine rather than an ordinary chewing gum product.
There is no single nicotine gum brand that is automatically the best for every person. The appropriate product and strength depend on individual circumstances, and consumers should follow the label and consult a doctor or pharmacist when needed.
FAQs on Top Nicotine Gum Brands in India
What are the Top 8 Nicotine Gum Brands in India?
The brands covered are Nicotex, 2baconil, Ryze, Nicogum, Nicosure, Nicover, Nicosip and Nicorite. Availability can vary by pharmacy, location and product strength.
Which is the best nicotine gum in India?
There is no universally best nicotine gum for everyone. Nicotine gum is an NRT medicine, and the appropriate strength and product depend on factors such as nicotine dependence and individual health circumstances.
What is nicotine gum used for?
Nicotine gum is used as nicotine replacement therapy to help reduce nicotine cravings and withdrawal symptoms while a person attempts to stop tobacco use.
Is nicotine gum safer than smoking?
NRT provides nicotine without the harmful chemicals produced by burning tobacco. WHO recommends NRT as one pharmacological option for adults who want to quit tobacco.
What strengths of nicotine gum are available in India?
Common strengths include 2mg and 4mg, although availability varies by brand. The appropriate strength should be selected according to product directions and, when appropriate, professional medical advice.
Can nicotine gum be used while smoking?
Consumers should not assume that they can freely combine nicotine gum with continued smoking. Product-specific instructions should be followed, and a doctor or pharmacist can provide guidance about NRT use.
How should nicotine gum be used?
Nicotine gum should generally not be chewed continuously like ordinary chewing gum. Specific instructions vary by product. Nicotex, for example, instructs users to chew slowly and then park the gum between the cheek and gum.
Is nicotine gum addictive?
Nicotine is an addictive substance, which is why nicotine gum should be used as directed as part of a cessation approach. Consumers having difficulty stopping NRT should speak with a healthcare professional.
-
India’s at-home services market is evolving as consumers increasingly seek professional beauty treatments, grooming, appliance repairs, and household support without leaving their homes. Digital platforms are bringing these services online, creating oppor
-
Digital-first beauty companies are expanding their physical presence to complement online sales. The move reflects changing shopping preferences and the growing importance of omnichannel retail in India.
-
The Sleep Company is scaling its retail-led business, targeting Rs. 1,000 crore in revenue through store expansion, product diversification and deeper market penetration.
 Bla Bli Blu has turned EBITDA-positive as its annualised revenue run rate reaches Rs 250 crore. The fragrance brand credits its business growth to its sales strategy, marketing partnerships and presence across e-commerce and quick-commerce channels.


Copyright © 2009 - 2026 Franchiseindia.com Ltd